

Blogs
PW Consulting: Luxury Sunglasses Market Hits $14.45B in 2025, Set for 4.59% CAGR Through 2032
By PW Consulting, 2026-09-16
The Strategic Imperative: Navigating the Luxury Sunglasses Market in 2026
The global accessory landscape is undergoing a subtle but profound transformation. Within this shift, the Luxury Sunglasses Market stands out as a beacon of resilience and sustained growth. For brand leaders, investors, and supply chain strategists, understanding the nuance of this sector is no longer optional; it is a critical component of long-term portfolio management. As we move through 2026, the intersection of timeless design, technological integration, and complex regulatory environments defines the operational terrain.
PW Consulting's latest comprehensive market research offers a detailed map of this terrain. This report is not merely a collection of statistics; it is a strategic toolkit designed to inform decision-making across product development, regional expansion, and competitive positioning. By analyzing historical trajectories and forecasting future trends, we provide the intelligence necessary to capitalize on emerging opportunities while mitigating the risks inherent in a fragmented market.
The following insights outline the current state of the industry and demonstrate why access to granular data is the ultimate competitive advantage in the coming fiscal years.
Macro Growth Trajectory and Market Valuation
The financial architecture of the luxury eyewear sector reveals a steady upward trend. Our analysis covers historical performance from 2020 through the base year of 2025, extending with precision into the forecast period of 2026 to 2032. This longitudinal view allows stakeholders to contextualize recent volatility against long-term growth patterns.
In 2025, the global market reached a valuation of approximately 14.45 billion USD. Looking ahead, the market is projected to expand to 14.95 billion USD in 2026, continuing its climb toward nearly 19.78 billion USD by 2032. This expansion reflects a Compound Annual Growth Rate (CAGR) of 4.59 percent over the forecast period. While these headline figures indicate healthy momentum, the drivers behind this growth are multifaceted, influenced by consumer behavior shifts, economic conditions, and product innovation.
For executives, the implication is clear: the market is large enough to support diverse strategies but competitive enough to demand precise execution. The steady CAGR suggests that organic growth is achievable, but capturing market share requires more than passive participation. It requires an understanding of where value is being created and how supply chain constraints might alter profitability margins.
The Competitive Landscape: Consolidation and Innovation
The luxury sunglasses sector is characterized by a moderate to high level of concentration. Our research indicates that the top three players hold a significant portion of the market revenue, while the top five firms command an even larger share. This concentration highlights the dominance of major conglomerates that manage multiple licensed and owned brands, though niche players continue to carve out premium positions through craftsmanship and brand heritage.
Several key companies define the current competitive hierarchy:
- EssilorLuxottica (Paris, France): As a market leader, this entity controls a vast portfolio including Ray-Ban, Oakley, and licensed luxury brands such as Tom Ford, Oliver Peoples, and Dolce & Gabbana. Their strategy blends mass appeal with high-end licensing.
- Marcolin Group (Italy): A crucial player in the production and distribution of designer luxury sunglasses, notably holding strong associations with Tom Ford eyewear.
- De Rigo Rem (Italy): Specializes in manufacturing and licensing luxury eyewear, with notable presence in brands like Police and Lozza.
- Safilo Group (Italy): Known for producing licensed luxury sunglasses for prestigious houses such as Gucci, maintaining strong ties to fashion heritage.
- Garrett Leight (United States): Represents the artisanal end of the market, designing and selling handcrafted luxury sunglasses with a focus on premium materials.
- Oliver Peoples (United States): Under EssilorLuxottica ownership, this brand continues to offer premium luxury sunglasses, leveraging its independent heritage within a larger corporate structure.
Strategic activity among these players is intensifying. For example, in March 2026, EssilorLuxottica extended its long-term licensing agreement with Dolce & Gabbana, securing development, production, and worldwide distribution rights for prescription frames and sunglasses. Simultaneously, they unveiled the first Oliver Peoples x Jil Sander sunglasses collection, featuring titanium and acetate frames with crystal lenses handmade in Japan. These moves signal a dual strategy: consolidating established luxury licenses while pushing the boundaries of material and fashion collaborations. Furthermore, the expansion of AI glasses portfolios, such as new Ray-Ban Meta optical styles for prescription wearers, indicates a convergence of wearable technology and traditional luxury aesthetics.
Market Dynamics and Regulatory Headwinds
No strategic plan is complete without accounting for external forces. The operational environment in 2026 is shaped by significant regulatory developments, particularly regarding trade policy. Recent updates from The Vision Council highlight substantial shifts in duty rates affecting the optical industry.
Imports of optical products from China have faced updated duty rates, with sunglasses encountering combined rates reaching 154.5 percent. This figure includes base duties, Section 301 tariffs, and reciprocal tariffs enacted in 2025. Such levels drastically impact landed costs and require immediate adjustments in pricing strategies and sourcing logic. In response to these pressures, major industry participants like EssilorLuxottica have implemented price increases in the US market to offset tariff impacts on imports from China and Thailand.
However, the regulatory landscape remains fluid. A 90-day pause on newly implemented country-specific reciprocal tariff increases was announced by the US Administration for countries that have not retaliated, effective April 2025. While this pause offers temporary relief, the underlying trade tensions suggest that supply chain diversification is no longer just a best practice but a necessity for risk mitigation. Companies relying heavily on single-source manufacturing hubs face elevated exposure, making the case for nearshoring or multi-regional production capabilities more compelling than ever.
Segmentation Insights: Where Value Resides
Understanding the composition of the market is vital for targeted investment. Our report dissects the market across three primary dimensions: Region, Type, and Application. While the aggregate numbers tell a story of growth, the segmentation data reveals where the profitability engines are located.
The market is distributed across major geographic zones, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct consumer behaviors. For instance, mature markets in Europe and North America continue to drive volume through established luxury channels, while Asia Pacific represents a dynamic zone of growing affluence and brand consciousness. Navigating these regional differences requires more than a one-size-fits-all approach; it demands localized marketing strategies and distribution partnerships that resonate with specific cultural nuances.
Product type segmentation further illustrates the evolution of consumer preference. The market is divided between Polarized, Non-polarized, and Other Types. The performance of polarized lenses reflects a growing demand for functional luxury, where eye protection and visual clarity are prioritized alongside style. Meanwhile, the non-polarized segment maintains a stronghold in fashion-forward contexts where aesthetics take precedence.
Application-based segmentation highlights the dual identity of luxury sunglasses. The Fashion application dominates the landscape, underscoring the role of eyewear as a critical accessory in personal style and identity. Sports and Other applications, while smaller in relative value, represent high-growth niches where performance materials and specialized designs command premium pricing. Recognizing the balance between these applications allows brands to allocate R&D resources effectively, ensuring they meet the demands of both the runway and the racecourse.
Luxury Sunglasses Market
The Strategic Value of Granular Intelligence
Headline figures and company profiles provide the context, but the true power of this research lies in the details that are not immediately visible. Strategic decisions regarding pricing elasticity, channel mix, and inventory management require access to specific volume data, share percentages, and trend velocity metrics.
For example, knowing the exact revenue split between regions helps determine where to prioritize expansion capital. Understanding the precise share of polarized versus non-polarized types informs product roadmap prioritization. Identifying the specific growth rate of the fashion application segment versus sports allows for nuanced marketing budget allocation. This report provides those specific data points, enabling clients to move beyond general assumptions to evidence-based planning.
Furthermore, the interplay between tariff structures and segmentation is critical. A tariff impact might affect one region or product type more severely than another. Only with detailed data can a company model these scenarios accurately and prepare contingency plans. The inclusion of recent developments, such as specific partnership extensions and product launches, also provides a benchmark for evaluating competitor aggression and innovation cycles.
The market concentration data served as a warning and an opportunity. For new entrants or smaller brands, the high concentration among the top players suggests high barriers to entry in mainstream luxury. However, the persistence of niche brands like Garrett Leight shows that differentiation through material quality and brand storytelling remains a viable path. The research helps identify the white spaces where concentration is lower and potential for disruption exists.
Looking Ahead: Actionable Intelligence for 2026 and Beyond
As we progress through 2026, the Luxury Sunglasses Market will continue to be shaped by the tension between heritage and innovation. Brands must honor the craftsmanship that defines luxury while integrating new technologies and adapting to regulatory shifts. The forecast period extending to 2032 offers a long-term view, allowing companies to plan beyond quarters and focus on sustainable growth.
Sunglasses Market
The data indicates that the market will continue to expand, reaching nearly 20 billion USD by the early 2030s. However, capturing this value requires agility. Supply chain resilience, pricing strategy adjustments, and brand differentiation are the pillars of success in this environment. Companies that rely on outdated assumptions about trade flows or consumer preferences risk margin erosion and loss of relevance.
PW Consulting's Luxury Sunglasses Market Research is designed to equip stakeholders with the clarity needed to navigate these complexities. By providing a comprehensive view of market size, segmentation, competitive dynamics, and regulatory impacts, we enable leadership teams to make informed choices. The insights contained within this report are not just observations; they are the foundation for strategy.
To fully leverage this intelligence, stakeholders must access the complete dataset. The intersection of macro trends and micro-segmentation data reveals the specific pathways to growth that headline numbers cannot show. We invite decision-makers to explore the full report to unlock the detailed analytics required to outmaneuver competitors and secure a dominant position in the evolving luxury eyewear landscape.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rainscreen Cladding Market Hits $169.2B in 2025, Projected to Hit $293.76B by 2032 at 8.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Rainscreen Cladding Market: Strategic Intelligence for 2026 and Beyond
The global construction industry stands at a critical juncture where aesthetic ambition must be reconciled with rigorous safety standards, material cost volatility, and evolving regulatory frameworks. Rainscreen cladding systems have emerged as a cornerstone of modern architectural design, offering critical benefits in moisture management, thermal insulation, and fire safety. For executives, investors, and strategic planners, understanding the trajectory of this market is not merely an academic exercise but a necessity for capitalizing on growth opportunities while mitigating systemic risks.
PW Consulting's latest comprehensive research on the Rainscreen Cladding Market provides a definitive roadmap for navigating these complexities. This study is designed to empower decision-makers with actionable intelligence, moving beyond surface-level observations to deliver a granular analysis of market drivers, competitive dynamics, and financial forecasts. As we look toward the forecast period extending to 2032, the data reveals a landscape defined by robust expansion, technological innovation, and shifting geopolitical pressures.
Market Trajectory and Financial Outlook
The historical performance of the rainscreen cladding sector underscores its resilience and growing importance in the built environment. Between 2020 and 2025, the market demonstrated consistent upward momentum, driven by a resurgence in construction activity and an heightened focus on building envelope performance. The total market revenue climbed from approximately $114.09 billion in 2020 to an estimated $169.2 billion in 2025. This growth trajectory reflects a compound annual growth rate that signals strong underlying demand across multiple verticals.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion. The market is anticipated to reach $181.66 billion in 2026, accelerating toward a projected value of $293.76 billion by 2032. This growth is underpinned by a CAGR of 8.2 percent, indicating that the sector will significantly outpace general construction market averages in many regions. However, realizing this potential requires a nuanced understanding of the forces shaping supply chains, material selection, and regional adoption rates. Our report dissects these variables, offering a clear view of where value is being created and where vulnerabilities lie.
Rainscreen Cladding Market
Product segmentation and Material Shifts
A critical component of strategic planning lies in understanding the divergence in material preferences and application demands. The market is segmented by type into Metal, Fiber Cement, Composite Material, and Ceramic solutions. Metal cladding continues to hold a dominant position, reflecting its versatility and durability, though it faces pressure from raw material cost fluctuations. Fiber Cement and Composite Material segments show substantial uptake, particularly where cost-efficiency and aesthetic flexibility are prioritized. Ceramic solutions, while smaller in volume, are gaining traction in high-end architectural projects demanding specific thermal and fire-resistant properties.
Application-wise, the Residential sector commands the largest share of demand, fueled by urbanization and a shift toward modern, energy-efficient housing designs. Commercial applications follow closely, driven by corporate office builds and retail expansions that prioritize facade branding and weather protection. Institutional and Industrial segments also contribute significantly, often governed by stricter compliance requirements that favor specialized cladding systems. The report provides a deep dive into how these segments interact with regional economic conditions and regulatory environments, allowing stakeholders to identify high-growth niches without exposing themselves to oversaturated or declining sub-markets.
Competitive Landscape: Leaders and Strategic Moves
The market structure is characterized by a mix of established multinational corporations and specialized regional providers. Our analysis identifies key players such as Kingspan Group plc, Rockwool International A/S, Cladding Corp, Alucobond, and Sotech Optima Company as pivotal actors influencing market direction. These companies are not merely competing on price; they are engaging in aggressive innovation and strategic positioning to capture market share.
Kingspan Group plc, headquartered in Ireland, remains a formidable force with its extensive portfolio of ventilated and non-ventilated rainscreen facades and insulation boards. In August 2025, the company announced a new range of eco-friendly rainscreen cladding products meeting stringent environmental standards, signaling a shift toward sustainability as a key differentiator. Similarly, Rockwool International A/S, based in Denmark, has strengthened its position by expanding production capacity in Europe with a new manufacturing facility in September 2025. This move aims to support rising demand for their BBA-approved stone wool insulation boards used in ventilated and sealed rainscreen systems, addressing both performance and supply reliability.
In the Americas, Cladding Corp, located in Camden, New Jersey, continues to serve as a vital provider of drained and back-ventilated systems for terracotta, fiber cement, ceramic, and porcelain panels, offering full engineering support that appeals to complex project requirements. Alucobond, operating from Germany, has focused on innovation in aluminum composite panels designed for pressure-equalized systems. Their strategic partnership with a leading architectural firm in July 2025 highlights a focus on developing innovative cladding solutions for high-rise buildings, where performance and aesthetics intersect. Meanwhile, Sotech Optima Company in the United Kingdom has launched the Optima BrickTech system in February 2025, a fully non-combustible rainscreen system offering the look of traditional brickwork with modern cladding performance, directly responding to fire safety concerns while maintaining design integrity.
The report delves deeper into the competitive dynamics, analyzing market concentration metrics such as CR3 and CR5 percentages to illustrate the balance of power. While these figures indicate a degree of consolidation among top players, there remains significant opportunity for agile competitors who can navigate local regulations and supply chain disruptions effectively.
Industry Dynamics: Regulatory and Economic Headwinds
No strategic assessment is complete without a rigorous examination of the external forces reshaping the market. The regulatory environment has become increasingly stringent, particularly regarding fire safety. In the UK, the government has implemented a complete ban on Metal Composite Material with unmodified polyethylene core in rainscreen cladding for all new buildings under the revised Approved Document B of the Building Regulations. This regulation, coupled with the requirements of the Building Safety Act which mandates stricter testing and certification following the Grenfell Tower inquiry, has fundamentally altered material preferences in the region. Similarly, local building codes in states such as California and New York increasingly mandate non-combustible materials for buildings over four stories, favoring metal and stone wool rainscreen systems.
Worldwide Wall Cladding Market
Economic factors also play a decisive role. Raw material cost volatility presents a significant challenge. Aluminum prices rose by over 30 percent from December 2024 into 2025, while steel prices increased nearly 17 percent, directly raising costs for architectural metal cladding components. These pressures are compounded by trade policy shifts. The US Environmental Protection Agency imposed a 50 percent import tariff on aluminum and steel products under Section 232 tariffs, effective April 2026, increasing costs for imported rainscreen cladding materials. These dynamics create a complex cost environment where pricing strategies, supply chain localization, and material substitution become critical success factors. Our research analyzes how these headwinds impact margins and advises on mitigation strategies.
Scope of Comprehensive Analysis
PW Consulting's Rainscreen Cladding Market report is engineered to provide end-to-end visibility for strategic planning. The study encompasses a detailed analysis of market size and growth forecasts, segmented by region, type, and application, allowing stakeholders to benchmark their performance against broader industry trends. It includes a thorough examination of the competitive landscape, profiling key companies with insights into their product portfolios, recent developments, and strategic initiatives.
Beyond quantitative data, the report offers qualitative insights into market dynamics, including the impact of regulatory changes, raw material price fluctuations, and technological advancements. It provides a review of historical performance from 2020 to 2025 to contextualize current market conditions and validate forecasting models. The forecast period through 2032 is analyzed with scenario-based projections to account for potential disruptions. Additionally, the research explores supply chain structures, identifies barriers to entry, and highlights emerging trends such as the integration of living wall systems and eco-friendly materials. This holistic approach ensures that readers gain a 360-degree view of the market, enabling informed decisions on product development, market entry, partnership formation, and investment allocation.
Strategic Imperatives for 2026 and Beyond
As the market moves into 2026, the convergence of growth opportunities and regulatory constraints demands a proactive stance. Companies must balance the push for innovative, sustainable products with the need to manage rising input costs and navigate complex compliance landscapes. The ban on certain composite materials in key regions necessitates a re-evaluation of product lines, while tariffs on metals require supply chain resilience and potential localization strategies. The expansion of capacity by major players like Rockwool underscores the importance of securing reliable supply channels, while product launches focused on non-combustibility and eco-friendliness highlight the shifting priorities of architects and developers.
This report serves as an essential tool for organizations aiming to thrive in this evolving environment. By leveraging the data-driven insights and strategic analysis provided, stakeholders can identify high-value segments, anticipate regulatory shifts, and align their portfolios with market demands. Whether you are a manufacturer seeking to expand your footprint, a distributor looking to optimize your inventory, or an investor evaluating market potential, this research delivers the depth and precision required to navigate the future of rainscreen cladding with confidence. The detailed forecasts, competitor benchmarks, and dynamic analysis contained within are designed to transform uncertainty into actionable strategy.
For a complete understanding of the global rainscreen cladding market, including detailed regional breakdowns, application-specific growth rates, and financial modeling, we invite you to access the full report. The data presented here offers a strategic overview, but the full intelligence package provides the granular detail necessary to execute with precision. Explore the findings in depth to secure your competitive advantage in a market poised for significant transformation.
For detailed analysis of this topic, please visit the official page: Rainscreen Cladding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radar Level Transmitters Market Hits $606.11M in 2025, Forecasting $894M by 2032 at 5.69% CAGR
By PW Consulting, 2026-09-16
Radar Level Transmitters Market 2026: Strategic Intelligence for Industrial Automation Leaders
The industrial automation landscape is undergoing a profound transformation, driven by stringent regulatory frameworks, the integration of IoT-enabled diagnostics, and a persistent demand for precision in hazardous environments. For stakeholders operating within the process industries, understanding the trajectory of level measurement technology is no longer optional—it is a critical component of capital allocation and operational resilience. PW Consulting is pleased to introduce our comprehensive market research study on the Radar Level Transmitters Market, designed specifically to equip decision-makers with the foresight required to navigate the period from 2026 through 2032.
This report serves as a strategic compass. While the broader industrial sector faces volatility, the radar level transmitter segment demonstrates a resilient growth trajectory grounded in technological maturation and regulatory compliance. Our analysis moves beyond surface-level observations to unpack the underlying mechanics of market expansion, competitive positioning, and the shifting value chain. By leveraging historical data from 2020 to 2025 and projecting forward, we provide a clear picture of where revenue opportunities will concentrate and how technology adoption curves are likely to unfold.
Executive Summary: Market Trajectory and Growth Dynamics
The global market for radar level transmitters has established itself as a cornerstone of modern process instrumentation. Based on historical performance from 2020 through 2025, the market has shown consistent upward momentum, reflecting the broader industrial shift away from traditional gauging methods toward non-contact and advanced guided wave solutions. The market revenue, measured in USD Million, has evolved significantly over the last half-decade, moving from a baseline of 425.0 in 2020 to an estimated 606.11 in 2025.
This historical growth sets the stage for the forecast period. As we look toward 2026, the market is positioned at an estimated 622.3, indicating a continuation of positive momentum. Over the long-term forecast horizon ending in 2032, the market is projected to reach 894.0. This expansion is underpinned by a compound annual growth rate (CAGR) of 5.69 percent during the forecast period. Such a rate suggests steady, sustainable growth rather than speculative bubbles, making this sector attractive for long-term investment and operational planning.
Worldwide Electronic Transmitters Market
The growth is not uniform across all segments. The transition from legacy technologies to 80 GHz radar solutions is a primary driver. For instance, recent industry developments highlight a surge in product launches and certifications tailored to specific regulatory needs. In April 2025, SKE launched its new 80 GHz SKE series radar level transmitter, featuring integrated molding technology aimed at improved performance. Similarly, Emerson launched the Rosemount 1208 wireless non-contacting radar level transmitter in October 2025, focusing on simplified installation for utility and process applications. These launches indicate a market trend toward wireless connectivity, compact design, and ease of integration.
Furthermore, the competitive landscape is characterized by moderate concentration. With a CR3 of 28.5 percent and a CR5 of 53.4 percent, the market remains accessible to a variety of players while maintaining strong leadership from established multinational corporations. This balance suggests that while market leaders hold significant sway, there is ample space for specialized innovators to capture niche segments through differentiation in frequency, certification, or connectivity.
Regulatory Tailwinds and Industry Dynamics
One of the most critical aspects of our analysis focuses on the external forces reshaping demand. Regulation is no longer just a compliance hurdle; it is a market accelerator. In Europe, for example, regulations mandating advanced overfill protection have prompted operators to replace ultrasonic gauges with 80 GHz radar solutions. This shift is not merely technical but operational, as radar offers superior performance in challenging conditions such as vapor, dust, and turbulence.
Simultaneously, methane-emission rules in Europe require tighter tank-gauging accuracy. This regulatory pressure is driving the adoption of 80 GHz radar sensors that can meet these stringent accuracy standards, thereby reducing leaks and environmental impact. In the United States, certification agencies have cleared W-band (76-81 GHz) sensors for process use. This clearance is driving scale economies and eroding price premiums, making advanced technology more accessible to a broader range of industrial clients.
Safety certifications remain a pivotal differentiator. VEGA achieved MCERTS Class 1, WRAS, and Ex ia ATEX certifications for VEGAPULS smart compact radar level sensors in August 2025. This achievement enables use in UK water, wastewater, and hazardous applications, opening up specific verticals that require rigorous safety validation. Similarly, SKE 80 GHz radar level sensors received TÜV NORD SIL2/SIL3 certification, reinforcing the importance of functional safety in critical process industries. These certifications are not just badges; they are prerequisites for entry into regulated markets, and our report details how these compliance landscapes affect market penetration strategies.
Competitive Landscape and Strategic Positioning
The radar level transmitter market is contested by a robust mix of global automation giants and specialized instrumentation firms. The competitive environment is defined by innovation in frequency modulation, wireless connectivity, and integration with broader process control systems. Our report provides an in-depth profiling of key companies that are shaping this landscape, analyzing their product portfolios, strategic moves, and regional strengths.
Radar Level Transmitters Market
Among the leaders, Emerson Electric Co. continues to strengthen its position with the Rosemount series, including the 3408 and 5408 models for liquids, solids, and interface measurement. Their focus on smart diagnostics and wireless options aligns with the industry's move toward Industry 4.0. Endress+Hauser Group maintains a strong foothold with its Micropilot and FMR series 80 GHz radar level transmitters, particularly noted for high precision and hygienic certifications suitable for process liquids, slurries, and solids.
Siemens AG competes with the SITRANS series, emphasizing advanced signal processing and IoT integration for industrial process monitoring. ABB Ltd. supplies both guided wave and non-contact models, including the LWT series, which are critical for total and interface level measurement in harsh environments. VEGA Grieshaber KG remains a key player with the VEGAPULS series, offering 80 GHz radar level sensors with Bluetooth connectivity and compact design, catering specifically to water, wastewater, and hazardous applications.
Other significant contributors include KROHNE Messtechnik GmbH, which introduced the OPTIWAVE 1500 series in October 2025 with expanded models 1520 and 1540, further diversifying their liquid and solids measurement capabilities. Honeywell International Inc. includes radar level transmitters in its broader automation portfolio, while Yokogawa Electric Corporation manufactures solutions tailored for the chemical, oil, and gas industries. Ametek, Inc., through Magnetrol International, offers Pulsar and other radar level transmitters for liquids, slurries, and solids, leveraging its reputation for bulk solids measurement.
The market also includes regional specialists and niche providers such as Automation Products Group (APG) with its TRUE ECHO series explosion-proof pulse radar level transmitters for hazardous locations, and Nivelco Process Control Ltd., which released its 2026 product catalog featuring new PiloTREK WP–200 and WT–300 compact 80 GHz FMCW radar level transmitters. Companies like KOBOLD Instruments, FINE-TEK Co., Ltd., WIKA Alexander Wiegand SE & Co. KG, and Pepperl+Fuchs SE round out the competitive field, each bringing specific strengths in installation ease, sensor portability, or specific industrial verticals. This diversity ensures that while the market is concentrated, it remains dynamic and responsive to varied customer needs.
Product Segmentation and Application Trends
Understanding how the market splits across technology types and applications is vital for targeting sales efforts and procurement strategies. The market is primarily divided into contact and non-contact technologies. Non-contact solutions, including Pulsed Radar and FMCW Radar, continue to gain favor due to their versatility and reduced maintenance requirements compared to contact methods. Guided Wave Radar remains essential for specific interface measurements where precision is paramount.
In terms of application, the demand spans across liquids, slurries, interfaces, and solids. The handling of solids represents a significant portion of the use cases, driven by industries such as mining, cement, and bulk chemical storage. Liquids and slurries remain the traditional stronghold, particularly in oil and gas, water and wastewater, and pharmaceutical sectors. Our report dissects these segments to reveal which combinations of type and application are yielding the highest growth margins.
Recent developments suggest a convergence in technology capabilities. The introduction of 80 GHz sensors across multiple brands—such as KROHNE, VEGA, SKE, and Nivelco—indicates a standardization of high-frequency technology as the benchmark for performance. This standardization allows buyers to compare specifications more easily but also raises the bar for performance across the board. Integration into process control systems is another key trend, with manufacturers ensuring their transmitters communicate seamlessly with PLCs and SCADA systems, reducing engineering time and installation costs.
Strategic Recommendations for 2026 Decision Makers
As enterprises plan their capital expenditures and technology roadmaps for 2026 and beyond, several strategic imperatives emerge from our analysis. First, regulatory compliance should be viewed as a procurement criterion rather than an afterthought. With methane-emission rules and overfill protection mandates tightening, selecting transmitters that already hold necessary certifications like ATEX, SIL, and MCERTS can mitigate project delays and operational risks.
Second, the shift toward wireless and IoT-integrated solutions offers an opportunity to reduce lifecycle costs. The launch of products like the Rosemount 1208 wireless transmitter highlights the industry's direction. Investing in infrastructure that supports wireless connectivity can simplify installation in remote or hazardous locations, where cabling is costly and dangerous.
Third, supply chain resilience and vendor stability are crucial. With a CR5 of 53.4 percent, the top five players hold a majority share, providing a level of stability and support capacity that smaller vendors may struggle to match. However, the presence of agile specialists means that for niche applications, partnering with vendors who offer specialized engineering support can yield better operational outcomes than relying solely on generic large-scale solutions.
Finally, staying abreast of technological standardization is key. As 80 GHz becomes the norm for high-performance applications, legacy 26 GHz systems may face obsolescence pressure in critical environments. Procurement teams should evaluate existing installed bases against these emerging standards to plan for phased upgrades that maintain accuracy and compliance without unnecessary capital waste.
Accessing Comprehensive Market Intelligence
This article provides a strategic overview of the Radar Level Transmitters Market, highlighting the macro-economic trends, regulatory drivers, and competitive shifts that define the landscape. However, the full depth of our research extends far beyond these high-level insights. For organizations seeking to make data-backed decisions regarding market entry, expansion, or procurement, the granular details are essential.
Our complete market research report offers detailed segmentation analysis, historical data tables, and forecast models that quantify growth across specific regions and application verticals. We provide exhaustive company profiles, analyzing strategic moves, product launch timelines, and financial positioning of the key players. Furthermore, the report includes an assessment of market concentration, pricing dynamics, and the specific impact of regulatory changes on supply and demand curves.
To leverage this intelligence for your strategic planning, we invite you to access the full Radar Level Transmitters Market Research report. The comprehensive dataset within will empower your team to identify untapped opportunities, benchmark against competitors, and align your technology investments with the projected market trajectory through 2032. Do not rely on fragmented information when precise intelligence is available. Engage with the full study to secure a competitive advantage in the evolving industrial automation sector.
For detailed analysis of this topic, please visit the official page: Radar Level Transmitters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flooring Underlayment Market to Reach $2.7B by 2032 with 4.8% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for a Resilient Floor: Inside the 2026 Flooring Underlayment Market Outlook
The flooring underlayment market is entering a decisive phase of commercial maturity, where incremental growth hides complex structural shifts. For executives navigating procurement, product development, or channel strategy in 2026, surface-level demand signals are no longer sufficient. What matters now is the interaction between raw-material volatility, regional manufacturing footprints, warranty-driven performance standards, and the quiet consolidation shaping competitive positioning. Our newly released market research distills these forces into an actionable framework, giving leadership teams a reliable basis for capital allocation, pricing discipline, and portfolio planning through the end of the decade.
The numbers tell a story of steady expansion rather than explosive disruption. Between 2020 and 2025, the global market climbed from roughly $1.53 billion to $1.94 billion, reflecting a cumulative push built on residential renovation, commercial retrofit programs, and a broader shift toward performance-oriented floor systems. Heading forward, the forecast period from 2026 to 2032 points to continued upward momentum, with the market trajectory implying a compound annual growth rate of 4.8 percent. That pace is significant not because it is dramatic, but because it is durable: it signals an industry where growth is increasingly tied to specification quality, installer behavior, and material innovation rather than simple volume replacement.
Yet durable growth creates a more demanding decision environment. A market expanding at this speed still remains structurally fragmented at the top. Concentration metrics indicate that the three largest players account for approximately 42.5 percent of revenue, while the top five hold around 58.2 percent. In practical terms, that means scale advantages exist, but they are not yet absolute. Regional demand patterns, application-specific requirements, and material preferences continue to create differentiated opportunity zones. Our research maps these zones without reducing them to oversimplified rankings, allowing decision-makers to see where intensity is rising and where margins are most exposed.
The strategic value of this report lies in its operational focus. Rather than stopping at top-line forecasts, it integrates the market numbers with the mechanics that actually shape profitability: raw-material input dynamics, regulatory and warranty constraints, labor and installation practices, and the pricing pressures emerging from trade and transportation costs. These are the variables that determine whether a company can convert demand into margin. In 2026, that conversion is anything but automatic.
What the Research Delivers
This study is designed as a decision-grade reference for executives who need to anticipate shifts before they become visible in quarterly results. The analysis combines historical performance tracking with forward-looking scenarios, allowing readers to test assumptions against a structured baseline. The report examines how demand is forming across residential, commercial, and industrial applications, and it evaluates how material types are competing for share in increasingly specification-driven environments.
Beyond segmentation, the research digs into the operational realities that separate resilient operators from those simply riding market growth. It assesses how manufacturers are responding to raw-material cost sensitivity, especially where polyethylene-based foam remains central to dominant product categories and pricing tracks closely with crude oil movements and refinery capacity conditions. It also examines how recycled rubber and natural cork formulations are being rebalanced after the supply disruptions of 2022 and 2023, enabling a number of producers to revisit capacity expansion with greater confidence.
Equally important, the report addresses the commercial constraints that define product viability. Underlayment performance is not merely a technical question; it is a warranty question. For resilient flooring, manufacturers commonly require underlayment to remain within strict thickness limits, often capping total build at around 3 millimeters to prevent stress on locking joints and avoid voiding warranties. This constraint shapes product design, installation guidance, and competitive differentiation in ways that many market summaries overlook. Our analysis places these limitations in context so that strategy teams can evaluate where performance claims are credible and where they risk creating downstream friction.
Flooring Underlayment Market
The research also incorporates the cost pressures that are reshaping sourcing and import planning. Tariffs are increasing expenses tied to imported foam materials, rubber components, and cork, while transportation surcharges continue to influence landed costs. For companies operating across multiple regions, these pressures do not simply raise prices; they alter the economics of channel selection, inventory positioning, and supplier diversification. By mapping these dynamics alongside regional demand intensity, the report helps leaders identify where cost absorption is feasible and where it is not.
Competitive Landscape: Scale, Specialization, and Recent Moves
The competitive environment reflects a blend of broad-capability incumbents and smaller specialists competing on acoustics, moisture control, sustainability, and application-specific performance. The market is not defined by a single product philosophy. Instead, it is shaped by manufacturers who are pursuing different answers to the same core question: how to deliver sound reduction, moisture protection, and installation reliability without breaking warranty constraints or exposing the buyer to excessive cost volatility.
Several companies illustrate the strategic range now visible in the sector. MP Global Products, based in Norfolk, Nebraska, has built recognition around acoustic fiber underlayments marketed under the QuietWalk brand for hardwood, laminate, and vinyl flooring. Its emphasis on noise reduction, moisture protection, and recycled content reflects a broader industry push toward environmentally conscious formulations that still meet performance expectations in residential and commercial settings. Leggett & Platt Flooring Products remains a major U.S. force in carpet cushion and hard-surface underlayment, offering foam, rubber, and other formulations tailored to laminate, vinyl, and engineered wood applications. Its breadth positions it as a supplier that can address multiple floor types within a single procurement relationship.
Pak-Lite, Inc. occupies a distinctive niche as a large private-label manufacturer of floating wood and laminate flooring underlayment in North America, with customized products structured around IIC, STC, and Delta performance ratings. That rating-centered approach matters because it aligns product selection with measurable acoustic outcomes, an increasingly important factor for specification-driven projects. Wise Flooring Products LLC, in Old Hickory, Tennessee, focuses on recyclable, American-made underlayment for residential and commercial applications, reinforcing a domestic-production value proposition that resonates in certain procurement environments. FloorMuffler contributes a portfolio spanning XLPP foam, rubber, and recycled-fiber underlayments, including product lines such as FloorMuffler UltraSeal, Natura, and FloorMat, all oriented toward sound insulation and moisture protection beneath vinyl, laminate, and hardwood.
Regional manufacturing presence is also expanding the field. Cyg Tefa, based in Vietnam, supplies high-density IXPE foam underlayment for luxury vinyl plank, laminate, and wood flooring, with an emphasis on soundproofing and moisture resistance. Hubei Xiangyuan New Material Technology Inc. operates as a professional manufacturer offering multiple underlayment types for different flooring applications, reflecting the broader diversification of Asian material supply capacity. RSP Industries, Inc. rounds out the competitive picture as a manufacturer of acoustic underlayment products, adding another voice to a market where sound performance is becoming a primary purchase criterion.
Roofing Underlying Materials Market
Recent activity in 2026 underscores how actively companies are trying to reshape category expectations. In May 2026, Floordi introduced F-Shield Underlayment, a premium acoustic solution intended to improve floor stability, enhance acoustic comfort, and add moisture protection for modern flooring systems. The launch signals continued investment in higher-performance formulations rather than basic cushioning. In April 2026, MP Global Products promoted its range of eco-friendly acoustic underlayments, emphasizing recycled material usage alongside noise reduction and moisture control. Earlier, in January 2026, Cyg Tefa showcased advanced IXPE and XPE foam underlayment solutions at Vietbuild Hanoi 2025, highlighting soundproofing, moisture resistance, and suitability for LVP, laminate, and wood flooring, with reported interest from manufacturers and distributors.
These moves matter because they reveal where the market is trying to earn higher margins: through better acoustic performance, stronger moisture management, and clearer sustainability storytelling. They also show that competition is no longer confined to price per square foot. As specifiers and installers become more attentive to warranty compatibility and long-term floor stability, companies that can credibly demonstrate performance across multiple criteria are better positioned to defend pricing and win repeat business.
Market Dynamics Shaping 2026 Decisions
The operational context of the underlayment market is being reshaped by a small number of powerful forces. Raw-material sensitivity remains one of the most important. Polyethylene foam continues to serve as a primary input for the dominant foam-based underlayment category, which means pricing exposure is closely linked to crude oil swings and refinery capacity constraints. In a market growing at a mid-single-digit pace, input volatility can quickly alter the profitability of otherwise successful product lines. Companies that rely on a narrow material base face greater risk than those with diversified formulations or stronger hedging and sourcing strategies.
At the same time, supply chain normalization is creating new strategic room. Recycled rubber and natural cork remain common in underlayment formulations, and the stabilization of supply after the disruptions of 2022 and 2023 has allowed some manufacturers to move more confidently toward capacity expansion. That shift is not merely operational; it has strategic implications for lead times, regional fulfillment, and the ability to support product launches with reliable inventory. In practical terms, normalized supply can become a competitive advantage when paired with the right application focus.
Regulatory and warranty constraints are equally important. Underlayment must meet manufacturer warranty requirements for resilient flooring, and those requirements often include strict limits on total thickness, typically capping build at about 3 millimeters to avoid excessive stress on locking joints and the risk of voiding warranties. This reality limits the scope for oversized product claims and pushes differentiation toward material density, acoustic ratings, moisture behavior, and installation consistency. For strategy teams, it means that the most defensible product narratives are those aligned with accepted installation parameters rather than speculative performance extremes.
Trade exposure is another pressure point. Tariffs are increasing costs for imported foam materials, rubber components, and cork used in underlayment production, while transportation surcharges add further complexity to landed-cost calculations. These effects vary by sourcing footprint, but they consistently influence the relative attractiveness of domestic production, regional sourcing, and inventory buffering. Companies that treat these costs as static will likely misjudge margin durability. Those that incorporate them into scenario planning will be better prepared to adjust pricing, revise supplier mixes, or shift demand toward less exposed product lines.
Labor and installation dynamics also deserve attention. In the U.S. market, moisture mitigation systems and installer-focused innovation are influencing labor requirements for floor prep and underlayment installation. This matters because installation friction can determine adoption rates just as much as product specification. If a solution is technically strong but difficult to deploy consistently across job sites, its commercial advantage may be limited. Conversely, installer-friendly designs can improve throughput, reduce rework, and strengthen end-user satisfaction, all of which support repeat demand and specification lock-in.
How to Use This Research in 2026
The report is structured to support several high-value decisions at once. For product and innovation teams, it provides a baseline for assessing which performance attributes are gaining commercial weight and where claims must remain closely aligned with warranty and installation constraints. For sourcing and operations leaders, it connects material volatility and trade exposure to practical choices about supplier diversity, inventory posture, and regional fulfillment. For commercial and sales leadership, it helps explain why the market is increasingly rewarding specification credibility, acoustic performance, and moisture management over simple cost positioning.
Most importantly, the research is built to support scenario-based planning. A market expanding at a 4.8 percent CAGR over the 2026 to 2032 forecast period is not a market where a single strategy will remain optimal for long. Different regions, applications, and material types will respond unevenly to cost pressures, demand shifts, and competitive launches. The report helps leadership teams anticipate that unevenness, identify where concentration and fragmentation intersect, and evaluate which moves are likely to strengthen positioning versus merely preserve share.
This overview is intended as a strategic preview, not a complete substitute for the full analysis. The underlying report contains the detailed segmentation structures, competitive benchmarking, and operational insights needed to translate market direction into executable plans. For organizations preparing budgets, expansion choices, or product roadmaps for the remainder of the decade, that deeper intelligence is where uncertainty becomes manageable and strategy becomes durable.
For detailed analysis of this topic, please visit the official page: Flooring Underlayment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Safety Glasses Market Reaches USD 225.5M in 2025, Growing at 4.05% CAGR
By PW Consulting, 2026-09-16
Strategic Foresight in Eye Protection: Navigating the Safety Glasses Market Through 2032
Executive Introduction
The safety glasses market stands at a critical intersection of regulatory evolution, material innovation, and operational safety prioritization. As we move through the mid-2020s, enterprises across industrial, construction, and manufacturing sectors face mounting pressure to align procurement strategies with updated compliance frameworks and shifting demand patterns. This article introduces PW Consulting latest comprehensive market research on the Safety Glasses Market, designed to equip decision-makers with the strategic intelligence required for 2026 planning and beyond. Rather than offering surface-level demand estimates, our analysis dissects the underlying structural drivers, competitive positioning, and compliance dynamics that will shape purchasing decisions, product development roadmaps, and regional expansion strategies over the next seven years.
For procurement leaders, product managers, and corporate strategists, the question is no longer whether the market will grow, but how to capture margin, mitigate supply chain volatility, and future-proof inventory against evolving safety standards. Our latest research delivers a granular, forward-looking view of the landscape, translating macro trends into actionable intelligence tailored for enterprise-level decision-making.
Market Trajectory and Structural Drivers
Over the historical period from 2020 to 2025, the global safety glasses market has demonstrated steady expansion, reflecting sustained investment in occupational health, manufacturing output, and construction activity. Total market revenue has progressed from approximately 185.2 million USD in 2020 to an estimated 225.5 million USD by 2025, underscoring consistent demand absorption across mature and emerging ecosystems. Looking ahead, our forecast model projects the market to reach roughly 227.7 million USD in 2026, with continued expansion through 2032, culminating in an estimated 296.5 million USD.
This trajectory translates to a compound annual growth rate of 4.05 percent across the 2026 to 2032 forecast horizon. While the percentage may appear moderate at first glance, the strategic implication lies in the compounding effect on mid-to-high-tier product categories, where premium coatings, ballistic-rated frames, and prescription-compatible designs command stronger margins and longer replacement cycles. The 4.05 percent CAGR signals a market transitioning from volume-driven commodity sales toward value-driven performance specifications, demanding that buyers and suppliers recalibrate sourcing strategies accordingly.
Several structural drivers underpin this momentum. First, the ongoing renewal of occupational safety standards is reshaping certification requirements, pushing manufacturers and buyers to update product lines and compliance documentation. Second, industrial automation and advanced manufacturing workflows continue to introduce new hazard profiles, requiring eyewear that balances impact resistance with optical clarity and long-wear comfort. Third, construction sector expansions in multiple regions sustain baseline demand, while specialty applications, from chemical processing to radiation-prone environments, create differentiated demand pockets that reward niche engineering. Together, these forces create a market where strategic procurement and product positioning determine competitive advantage.
Competitive Landscape and Enterprise Positioning
The market exhibits a moderately fragmented but increasingly competitive structure, with top-tier players consolidating influence through brand recognition, certification portfolios, and coating technology leadership. Our concentration analysis indicates that the top three companies command approximately 35.5 percent of market revenue, while the top five players collectively account for roughly 52.3 percent. This distribution suggests that while scale players hold meaningful share, substantial opportunities remain for specialized manufacturers that can differentiate through ergonomic design, ANSI-aligned testing performance, and rapid catalog refresh cycles.
Among the leading enterprises shaping the landscape, Wiley X has established a strong reputation for ballistic and industrial safety glasses featuring advanced lens coatings engineered for high-impact and chemical resistance. Its positioning appeals to sectors where occupational hazards exceed standard impact thresholds, making its product lines particularly relevant for defense-adjacent, heavy manufacturing, and high-risk industrial buyers. Bollé Safety, based in France, emphasizes anti-fog and anti-scratch performance through its PLATINUM-coated portfolio, aligning with workplaces where temperature fluctuations, humidity, and particulate exposure degrade visual clarity and worker compliance. The company certification emphasis under ANSI Z87.1 and OSHA frameworks reinforces its relevance for compliance-sensitive procurement.
uvex Safety Group continues to expand its footprint with high-quality safety glasses and goggles that meet ANSI/ISEA Z87.1 standards, including prescription and specialized models. Its German engineering heritage and broad product breadth allow it to serve both general industry and specialized environments, while its ongoing participation in major trade platforms underscores its commitment to visible market engagement and product refreshes. MCR Safety, headquartered in the United States, focuses on ANSI Z87.1-compliant eye protection with military-grade and UV-blocking options, targeting industrial applications where prolonged outdoor exposure or high-intensity lighting conditions demand enhanced filtration and durable frame construction. Its recently updated catalog reflects a strategic push toward latest styles, advanced coatings, and ANSI Z87+ impact-rated options, indicating responsiveness to buyer preferences for both aesthetics and certified performance.
Honeywell and MSA Safety represent substantial industrial safety ecosystems, offering comprehensive safety glasses and goggles certified to ANSI Z87.1 for workplace impact, chemical, and splash protection, along with prescription options suited to general industry and construction. Their scale, distribution reach, and integration with broader PPE portfolios make them key reference points for enterprise buyers seeking streamlined vendor relationships. Essilor, through its prescription safety eyewear partnerships, bridges optical precision with compliance, working alongside frame manufacturers to deliver ANSI Z87.1 and OSHA-compliant prescription safety glasses that address a persistent pain point in jobs requiring corrected vision without sacrificing protection standards.
Radians Safety has gained attention for its GLYF™ and ballistic-rated safety eyewear compliant with ANSI Z87.1, emphasizing comfort and debris protection. Its recent product introductions, including ballistic-rated Crossfire BOLO™ eyewear showcased at major safety expos, illustrate how mid-tier players can gain momentum through targeted innovation and event-driven visibility. Meanwhile, Day Sun Industrial Corp. from Taiwan contributes ANSI Z87.1 and CE-certified safety glasses with anti-scratch and UV protection for industrial use, highlighting the continued role of cross-regional manufacturers in balancing cost efficiency with certified performance.
For enterprise strategists, this competitive environment demands a dual lens: evaluating incumbents on certification reliability, coating durability, and supply consistency, while monitoring emerging entrants that can rapidly iterate on lens technology, frame ergonomics, and ballistic-rated options. Our report maps these positioning dynamics in detail, helping buyers and suppliers identify where consolidation pressure is most intense and where white space remains for differentiated offerings.
Safety Glasses Market
Regulatory Dynamics and Compliance-Led Demand
Regulatory evolution is one of the most consequential forces shaping near-term procurement and product strategy. The Vision Council published ANSI/ISEA Z87.1-2025 in January 2026, marking the sixth revision of the voluntary consensus standard for occupational eye and face protection devices. This revision establishes updated criteria for testing, marking, and use across a broad range of occupational hazards, with a clear emphasis on harmonization with global standards and performance for diverse workplace conditions, including chemical and radiation exposure.
OSHA 1910.133 continues to anchor workplace requirements by mandating that safety glasses comply with recognized ANSI/ISEA standards. The current framework references earlier editions while also accepting the 2025 revision for hazard protection involving impact, radiation, and liquid splash. Equally important, OSHA mandates side shields for flying debris protection in general industry, reinforcing the operational relevance of frame design choices that balance coverage, peripheral visibility, and wearer compliance. The Z87 Committee on Safety Standards for Eye Protection developed the 2025 revision, which is then codified by OSHA for workplace requirements, creating a direct link between consensus testing protocols and enforceable employer obligations.
For buyers and product planners, these dynamics introduce both risk and opportunity. On the risk side, legacy inventory that does not align with updated marking, testing, or side-shield expectations may face procurement disqualification or compliance scrutiny. On the opportunity side, companies that proactively refresh catalogs with ANSI Z87.1-2025-aligned specifications can strengthen their value proposition to safety managers, reduce audit exposure, and position themselves as preferred vendors in compliance-driven tenders. Our research unpacks how these regulatory shifts interact with regional enforcement patterns, certification timelines, and manufacturer readiness, enabling enterprises to sequence product transitions and sourcing decisions with confidence.
What the Report Delivers for Decision-Makers
PW Consulting Safety Glasses Market research is structured to convert complex market signals into operational clarity. The report goes beyond headline figures to provide a practical toolkit for 2026 strategy formulation, procurement alignment, and competitive benchmarking. Below is a high-level overview of the actionable content included in the full study.
- Market sizing and trajectory analysis that traces historical performance and forecast pathways, giving leaders a clear baseline for demand planning and investment timing.
- Segment-level breakdowns across material types, application environments, and regional demand structures, enabling precise alignment between product portfolios and end-market requirements without oversimplifying complexity.
- Competitive benchmarking that evaluates major players on technology emphasis, certification alignment, product breadth, and market engagement, helping procurement teams compare vendor options against operational priorities.
- Regulatory impact assessment that maps ANSI/ISEA Z87.1-2025 updates and OSHA requirements to purchasing decisions, certification documentation, and product transition planning.
- Innovation and product lifecycle indicators that highlight coating advancements, ballistic-rated options, prescription-compatible designs, and comfort-driven ergonomics influencing repeat purchase behavior.
- Strategic implications for sourcing, inventory planning, and regional expansion, with guidance on where margin pressure is likely to intensify and where differentiated specifications can support premium positioning.
Each section is designed to support different internal stakeholders. Procurement leaders gain a clearer framework for evaluating supplier consistency, compliance readiness, and total cost of ownership. Product and innovation teams receive context on where coating technology, frame materials, and specialized models are gaining traction. Executives and strategy teams can use the forward-looking analysis to stress-test expansion plans, assess competitive exposure, and coordinate cross-functional safety procurement with broader operational goals.
Why This Research Matters for 2026 Strategy
The 2026 planning cycle demands more than a static snapshot. Market participants must reconcile steady overall growth with shifting demand composition, evolving compliance expectations, and intensifying competition among both global incumbents and specialized manufacturers. A 4.05 percent CAGR over the forecast period may appear measured, yet the underlying composition of growth, which materials lead, which applications expand fastest, and which regions absorb new capacity, will determine whether companies capture value or merely participate in the market.
One of the most important strategic takeaways is that compliance is becoming a differentiator, not just a baseline. As ANSI/ISEA Z87.1-2025 gains deployment and OSHA continues to reference updated standards, buyers are increasingly likely to favor product lines with clear certification alignment, documented testing, and updated marking protocols. Manufacturers that anticipate these expectations can shorten sales cycles and reduce friction in regulated procurement environments. At the same time, enterprises that delay portfolio alignment may face rising replacement costs and narrowing supplier options as legacy SKUs are phased out.
Another critical dimension is the growing importance of wearability and coating performance in sustaining compliance. Anti-fog, anti-scratch, and chemical-resistant coatings directly influence whether workers consistently use provided eyewear, which in turn affects incident rates, liability exposure, and safety program effectiveness. This makes product selection a strategic safety decision rather than a purely cost-driven purchase. Our report examines how these performance attributes correlate with demand patterns and competitive positioning, giving leaders a firmer basis for specification decisions.
Finally, the concentration profile of the market suggests that scale advantages matter, but they do not tell the full story. With the top five companies accounting for just over half of market revenue, a meaningful share of demand continues to flow to specialized providers that can serve distinct application requirements, offer prescription-compatible options, or deliver ballistic-rated performance. For buyers, this means vendor diversification can be strategically valuable when paired with rigorous compliance and quality evaluation. For suppliers, it means that targeted innovation and certification clarity can unlock share even in a moderately consolidated landscape.
Navigating the Opportunity with Precision Intelligence
As the safety glasses market advances through its forecast period, the organizations that outperform will be those that integrate demand forecasting, compliance readiness, and competitive intelligence into a single decision framework. PW Consulting latest research is built to support that integration. It provides the structural understanding needed to interpret market movement, the segment-level detail required to align product and procurement strategy, and the competitive context necessary to evaluate supplier options with confidence.
The full report expands on every dimension introduced here, delivering the depth required for 2026 planning and the forward view needed to anticipate 2027 through 2032 shifts. Readers seeking complete regional breakdowns, application-level demand structures, material-type segmentation, and enterprise-specific benchmarking will find those detailed insights accessible through the full study. This article serves as a strategic preview, outlining the market logic, compliance forces, and competitive dynamics that make the complete research essential for informed decision-making.
For executives, procurement leaders, and industry strategists committed to aligning safety procurement with operational performance and regulatory reality, the next step is clear: move from macro awareness to segment-level precision. The complete PW Consulting Safety Glasses Market research provides that precision, equipping your team with the intelligence needed to act decisively in 2026 and position your organization for durable advantage through 2032.
Sunglasses Market
For detailed analysis of this topic, please visit the official page: Safety Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Organizations Can Build a More Proactive Workplace Safety System
Workplace safety does not develop simply because an organization sends out reminders or reacts when something goes wrong. Sustainable improvement requires a consistent approach that helps people recognize hazards early and address them before they turn into incidents. When everyone uses a shared method for identifying hazards and preventive actions are supported by tools such as inspections, permits, and checklists, safety becomes integrated into everyday operations. It is no longer treated as a separate initiative. Instead, it becomes part of how work is prepared, managed, monitored, and carried out every day.
Understanding Workplace Hazards
A workplace hazard refers to any condition, task, substance, activity, or circumstance that has the potential to cause harm within a working environment. Its effects may include worker injuries, equipment damage, property loss, or disruptions to routine business activities. Hazards can arise from machinery, production processes, materials, workplace conditions, or the way specific jobs are performed.
Problems can occur when employees, supervisors, and contractors have different ideas about what constitutes a hazard. Reports may become inconsistent, risk assessments may reach different conclusions, and controls may be selected without addressing the actual danger. A useful way to create consistency is to group hazards into six broad categories. This gives teams a common framework for recognizing risks, classifying them correctly, and selecting appropriate preventive measures.
Six Major Categories of Workplace Hazards
- Safety Hazards
Safety hazards are usually among the easiest risks to notice because they can result in immediate injury. Examples include unprotected edges, floor openings, obstructed walkways, moving machinery or vehicles, and defective equipment. Since these hazards can produce consequences quickly, controls should be established before work begins.
Measures such as physical guarding, equipment isolation, permit requirements, and scheduled workplace inspections can help verify that necessary protections are present. They also help ensure safe conditions remain in place for the duration of the activity rather than being checked only at the beginning.
- Chemical Hazards
Chemical hazards are not always obvious. A substance may appear harmless while still having the potential to cause burns, poisoning, respiratory difficulties, or longer term health effects. Hazardous chemicals can be present in many forms, including liquids, gases, fumes, dust, vapors, and residual contamination.
Where possible, organizations can begin by replacing a hazardous substance with a safer alternative. Additional controls may involve containment, ventilation, clear labeling, exposure limitations, and suitable personal protective equipment. For higher risk activities, inspections and permit processes provide additional assurance that essential safeguards have been established before and while the work is taking place.
- Biological Hazards
Biological hazards arise when workers may come into contact with organisms or contaminated materials capable of causing infection or disease. These may include bacteria, viruses, fungi, insects, and other biological agents. Such risks can occur in healthcare facilities, laboratories, waste handling operations, food production areas, and outdoor work environments.
Effective management depends on reliable hygiene procedures, proper sanitation and cleaning, controlled access where necessary, and appropriate health related programs. Because these controls need to remain effective consistently, documented processes can help teams follow the required precautions instead of depending entirely on individual judgment.
- Physical Hazards
Some hazards may not produce an immediate visible effect, making them easier to overlook. Continued exposure to noise, vibration, radiation, poor lighting, or extreme temperatures can gradually affect worker health as well as job performance.
Organizations can monitor exposure, introduce engineering controls such as barriers or shielding, maintain equipment correctly, and adjust work schedules where necessary to reduce extended exposure. Addressing these conditions early can help prevent employees from experiencing prolonged contact with potentially harmful workplace environments.
- Ergonomic Hazards
Not every workplace injury happens suddenly. Repetitive tasks, awkward movements, poor posture, heavy lifting, and poorly arranged workstations can create physical problems over time. These ergonomic hazards can contribute to musculoskeletal injuries while also affecting productivity and operational efficiency.
Organizations can lower these risks by improving workstation layouts, redesigning tools, changing work methods, introducing safer lifting techniques, rotating tasks, and allowing appropriate recovery periods. When these practices are incorporated into standard procedures and reviewed through routine workplace assessments, they are more likely to remain effective rather than becoming temporary improvements.
- Psychosocial Hazards
Workplace safety also involves conditions that can affect employees beyond their physical surroundings. Excessive workloads, long working hours, unclear expectations, harassment, isolation, and inadequate support can influence concentration, judgment, and overall mental well being. These pressures may increase the possibility of mistakes and workplace incidents.
Managing psychosocial risks requires purposeful planning at the organizational level. Reasonable staffing, realistic schedules, clearly defined responsibilities, and dependable channels for raising concerns can contribute to a healthier working environment. A supportive workplace culture can strengthen these efforts by encouraging communication, appropriate assistance, and responsible reporting of problems.
Turning Risk Management into a Daily Habit
Identifying a hazard is only one part of effective safety management. The real objective is to ensure that corrective actions are implemented and continue working as intended. A practical safety cycle includes identifying the hazard, assessing the associated risk, determining suitable controls, and confirming that those controls are consistently followed whenever the activity occurs.
Digital workflows can help organizations apply this process more consistently across different teams, departments, and locations. Electronic permit to work systems can provide greater control over higher risk activities, including confined space entry and hot work. Lockout tagout procedures can be connected with equipment assets, helping teams verify that required isolation steps have been completed. Mobile checklists can also request supporting evidence, including photographs or QR code confirmation, before work receives authorization.
Used together, these capabilities can reduce procedural gaps, support compliance, and improve operational efficiency without removing essential safety requirements.
Connecting Safety Policies with Everyday Work
Paper based processes can result in incomplete records, delayed approvals, and inconsistent use of established procedures. Digital systems provide a more structured approach to managing accountability and compliance. When hazard categories, risk assessment methods, and control libraries are brought together within a common system, safety requirements can become easier for teams to understand and apply.
Supervisors can access required controls more quickly, employees can work from clearer instructions, and managers can use current information to monitor performance. Standardized templates can also promote consistency across different sites while giving teams enough flexibility to consider local conditions, contractor activities, and changing operational requirements.
A practical starting point is to examine routine work through the six hazard categories. Controls that are frequently required can then be incorporated into inspection and permit workflows as required steps. Mobile risk assessments can be completed directly where work is being performed, while dashboards can improve visibility by highlighting overdue actions and recurring issues that require additional attention.
When organizations apply this structured approach consistently, they can improve the management of near misses, reduce delays in approval processes, and strengthen audit performance. More importantly, safety stops being viewed simply as a compliance obligation. It becomes a dependable part of how the organization plans work, manages risk, and achieves operational excellence.
Book a free demo @ https://toolkitx.com/blogsdetails.aspx?title=Types-of-workplace-hazards:-examples,-and-how-to-control-them
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Safety-culture:-what-it-is,-why-it-matters,-and-how-to-build-it
https://toolkitx.com/blogsdetails.aspx?title=Hot-work-permit:-definition,-requirements,-and-practical-guide-to-going-digital
PW Consulting Report: Cs Beam and Hydrogen Maser Clocks Market Hits USD 40M in 2025, Projects 6.98% CAGR
By PW Consulting, 2026-09-16
Navigating the Precision Timing Revolution: Strategic Insights into the Cs Beam and Hydrogen Maser Atomic Clocks Market (2026–2032)
In an era where nanosecond precision dictates the reliability of global navigation, telecommunications, financial trading, and critical infrastructure, atomic clock technology has evolved from a specialized scientific instrument into a strategic asset class. The Cs beam and hydrogen maser atomic clocks market stands at a pivotal inflection point as nations, defense contractors, and telecommunications operators confront mounting threats from GNSS disruptions, space-based timing degradation, and escalating cybersecurity vulnerabilities. This comprehensive market intelligence study, anchored in historical performance from 2020 through 2025 and projecting forward to 2032, provides decision-makers with the analytical rigor required to navigate a highly concentrated yet rapidly commercializing landscape. By examining macro trajectory, competitive dynamics, technological substitution patterns, and regulatory catalysts, this report equips strategic planners, procurement leaders, and investment committees with actionable foresight for 2026 and beyond.
Market Trajectory and Structural Foundations
The market has demonstrated consistent expansion over the historical review period, climbing from 25.0 million USD in 2020 to an estimated 40.0 million USD in 2025. This growth trajectory reflects a compound annual growth rate of approximately 6.98 percent across the forecast window extending through 2032, with revenue projections indicating a continued upward arc driven by next-generation timing infrastructure, sovereign GNSS resilience initiatives, and the proliferation of precision-dependent applications in telecommunications and space exploration. The forecast period reveals a market that is scaling steadily rather than experiencing volatile spikes, underscoring the deliberate, engineering-intensive nature of atomic clock deployment and the long lifecycle characteristics of primary reference timing systems. By 2032, total market revenue is expected to surpass 60 million USD, illustrating sustained institutional and commercial demand for frequency standards that deliver unparalleled long-term stability and traceability to international timekeeping frameworks.
Several structural factors underpin this expansion. First, the growing deployment of optical cesium beam architectures and enhanced hydrogen maser platforms is broadening the addressable market beyond traditional national metrology laboratories and defense enterprises into commercial data centers, power grid synchronization networks, and next-generation telecommunications infrastructure. Second, the industry’s shift toward sovereign timing capabilities has accelerated procurement cycles, as governments and critical infrastructure operators seek to reduce reliance on vulnerable satellite-based timing signals. Third, the maturation of manufacturing ecosystems and the establishment of dedicated production lines for high-performance hydrogen masers are gradually improving supply chain reliability, reducing lead times, and expanding the commercial viability of these precision instruments. Together, these drivers create a durable growth foundation that strategic stakeholders can leverage to align product roadmaps, capacity planning, and partnership strategies.
Competitive Landscape and Strategic Positioning
The market exhibits a moderate-to-high concentration profile, with the top three participants collectively commanding a significant share of total revenue and the top five firms accounting for approximately half of the overall market. This concentration reflects the capital-intensive nature of precision timing research, the stringent certification requirements associated with primary frequency standards, and the long-standing intellectual property positions held by established players. However, the competitive environment is not static. Recent corporate developments underscore a sharp focus on manufacturing scalability, product diversification, and strategic deployment of atomic clock systems in high-stakes operational contexts.
- Microchip Technology Inc., headquartered in Chandler, Arizona, continues to reinforce its leadership in cesium beam frequency standards and active hydrogen maser solutions. The company’s MHM-2020 active hydrogen maser and 5071B cesium beam frequency standard have become reference architectures for metrology, telecommunications, and satellite applications requiring accuracies at the 5×10⁻¹³ level. In April 2026, the company inaugurated a new manufacturing facility in Tuscaloosa, Alabama, purpose-built to expand MHM-2020 production capacity, reduce delivery lead times, and address rising demand for independent timing systems in national infrastructure protection programs.
- Oscilloquartz SA, based in Neuchâtel, Switzerland, has extended its footprint through the OSA 3230 series of optical cesium beam atomic clocks and hydrogen maser solutions engineered for enhanced short-term stability via its ESTU module. The firm serves telecommunications, defense, and precision timing customers seeking compact, high-reliability architectures that bridge the performance gap between legacy cesium systems and premium hydrogen masers.
- Safran Electronics & Defense, operating from Paris, France, has emerged as a decisive player in spaceborne and ground-based atomic clock deployments. The Space Hydrogen Maser (SHM) powered the ESA ACES atomic clock ensemble aboard the International Space Station, achieving record stability for global timekeeping and deep-space applications. In September 2025, an all-European maser active hydrogen maser was deployed at the ESA New Norcia deep-space ground station in Australia, marking the first fully European ultra-precise maser operation for interplanetary missions and signaling a broader push toward sovereign timing sovereignty in deep-space communications.
- Adtran Inc., headquartered in Huntsville, Alabama, has strengthened its positioning through the integration of Oscilloquartz optical cesium beam clocks with ESTU modules, delivering hydrogen-maser-comparable short-term stability for data centers, power utilities, and defense PNT (positioning, navigation, and timing) applications. In June 2025, Adtran launched the Oscilloquartz OSA 3200 SP and OSA 3250 enhanced primary reference clocks, cost-effective optical cesium beam solutions with a 10-year lifespan and improved holdover capabilities designed to support telecom and infrastructure modernization efforts.
These developments reflect a competitive environment characterized by parallel strategies: vertical expansion into dedicated manufacturing capacity, cross-company technology integration, space mission validation, and product launches targeting cost-sensitive yet performance-critical segments. For buyers and partners, this landscape presents both consolidation opportunities and fragmentation risks. Organizations that map the competitive dynamics with precision can anticipate supply shifts, evaluate vendor lock-in exposure, and identify collaborative pathways that align with long-term timing resilience objectives.
Industry Dynamics: Regulation, Certification, and Technological Substitution
The market’s trajectory is increasingly shaped by regulatory milestones, standardization activities, and certification events that redefine performance benchmarks and procurement criteria. A notable catalyst occurred in April 2025, when the National Institute of Standards and Technology certified the NIST-F4 cesium fountain atomic clock as the new U.S. primary frequency standard, calibrated against hydrogen masers to improve UTC traceability and metrology applications. This certification effectively signals the transition away from legacy HP 5071A models in national metrology laboratories and establishes a new reference baseline that influences downstream procurement specifications across government and commercial sectors.
Simultaneously, the ESA ACES mission’s selection of Safran’s Space Hydrogen Maser in April 2025 underscores the strategic importance of exceptional short-term frequency stability for spaceborne applications. The deployment of an all-European maser active hydrogen maser at the New Norcia deep-space ground station in September 2025 further illustrates how certification and mission validation are converging to support sovereign deep-space tracking and GNSS resilience. These events are not isolated achievements; they represent structural shifts in how timing infrastructure is evaluated, deployed, and protected against environmental and geopolitical disruptions.
On the commercial side, Adtran’s June 2025 launch of Oscilloquartz optical cesium beam clocks with ESTU modules demonstrates a deliberate push to deliver hydrogen-maser-comparable short-term stability for Western defense and telecom PNT systems at a more accessible cost profile. This product evolution reflects a broader industry dynamic: the compression of performance gaps between cesium beam and hydrogen maser technologies, driven by module-level enhancements, improved holdover characteristics, and extended operational lifespans. As these dynamics mature, procurement teams must reassess the traditional dichotomy between cost and stability, particularly when evaluating deployment scenarios that demand rapid recovery from signal loss, long-duration holdover, or stringent synchronization tolerances.
Cs beam and Hydrogen Maser Atomic Clocks Market
What This Research Delivers: Operational Intelligence for 2026 Decision-Making
This market research study is designed as a decision-support toolkit rather than a static data summary. It provides a multi-layered examination of the Cs beam and hydrogen maser atomic clocks market, translating complex technical, commercial, and regulatory interdependencies into structured intelligence that can be operationalized across strategy, procurement, R&D, and investment functions. The report integrates historical performance data, forecast modeling, segment-level analysis, and competitive profiling to deliver a comprehensive view of market directionality and actionable differentiation points.
Core Analytical Components
- Macro market sizing and forecast modeling that contextualizes historical growth from 2020 through 2025 and projects revenue expansion through 2032, enabling scenario-based planning for capacity allocation, investment prioritization, and demand forecasting.
- Segment-level evaluation across technology types and regional markets, offering insight into how cesium beam and hydrogen maser architectures are positioned relative to one another, where adoption momentum is concentrating, and which demand drivers are most influential in shaping procurement strategies.
- Competitive profiling of incumbent and emerging participants, including corporate headquarters, product portfolios, accuracy and stability specifications, application footprints, and recent strategic developments that signal shifts in manufacturing scale, technology roadmaps, and market emphasis.
- Regulatory, certification, and standardization tracking that maps the impact of metrology lab transitions, space mission deployments, ground station operations, and product certifications on downstream procurement requirements and vendor qualification criteria.
- Market concentration and structural analysis that evaluates the implications of top-three and top-five share distribution for pricing dynamics, supply chain resilience, and partnership opportunities in a market where incumbency and certification heritage carry significant weight.
- Application-driven demand assessment that connects timing performance requirements to end-use environments—including telecommunications synchronization, defense PNT resilience, power grid stability, data center infrastructure, satellite operations, and deep-space communications—enabling stakeholders to align product strategy with real-world operational constraints.
Each component is constructed to support practical decision-making. Procurement leaders can use the segmentation and competitive profiling modules to evaluate supplier qualification criteria, benchmark performance specifications, and anticipate supply continuity risks. R&D and product management teams can leverage the regulatory and certification tracking sections to align development roadmaps with evolving metrology standards and space mission validation pathways. Strategy and corporate development functions can draw on the concentration analysis, regional demand signals, and technology substitution dynamics to identify partnership targets, geographic expansion priorities, and investment allocation frameworks.
Strategic Imperatives for 2026 and Beyond
As the market advances toward 2032, several strategic imperatives emerge for organizations operating within or adjacent to the precision timing ecosystem. First, sovereign timing resilience is transitioning from a policy aspiration to an operational requirement, and organizations that proactively align their timing infrastructure with independent, high-stability atomic clock solutions will be better positioned to mitigate GNSS disruption risks and comply with evolving national security and critical infrastructure mandates. Second, the convergence of optical cesium beam enhancements and hydrogen maser performance characteristics is reshaping the value proposition across price-performance tiers, requiring buyers and suppliers alike to reassess specification thresholds, total cost of ownership, and lifecycle support commitments. Third, manufacturing capacity expansions and dedicated production lines are gradually improving supply reliability, but lead time management, component sourcing, and qualification lead times remain critical considerations for deployment planning.
Fourth, space mission validation and deep-space ground station deployments are establishing new reference points for performance and reliability, creating pull-through effects that influence terrestrial procurement specifications and vendor evaluation criteria. Fifth, market concentration implies that strategic partnerships, long-term supply agreements, and dual-sourcing strategies may be necessary to balance performance requirements with supply chain resilience. Organizations that integrate these imperatives into their planning cycles will be better equipped to navigate a market that rewards technical precision, regulatory alignment, and strategic foresight in equal measure.
Conclusion: From Insight to Action
The Cs beam and hydrogen maser atomic clocks market is defined by its technical rigor, its growing strategic importance, and its steady expansion from specialized metrology and defense applications into broader commercial and infrastructure domains. The historical performance from 2020 through 2025 establishes a credible growth baseline, while the forecast through 2032 signals a market that continues to scale in response to sovereign timing initiatives, space mission deployments, telecommunications modernization, and critical infrastructure synchronization requirements. Competitive dynamics remain shaped by incumbency, certification heritage, and manufacturing scale, yet recent facility expansions, product launches, and mission validations demonstrate that the landscape is actively evolving.
For executives, procurement leaders, and strategic planners, the imperative is clear: precision timing is no longer a backend technical consideration but a front-line resilience priority. This market research study provides the structured intelligence required to translate that priority into informed decisions—whether those decisions involve vendor selection, technology roadmap alignment, geographic demand assessment, or investment prioritization. To access the full segmentation analysis, regional demand breakdowns, detailed competitive profiles, and forecast scenario modeling that underpin these strategic conclusions, stakeholders are invited to explore the complete report on our platform, where the complete intelligence is available to support your 2026 planning cycle and beyond.
Rubidium Atomic Clock Market
For detailed analysis of this topic, please visit the official page: Cs beam and Hydrogen Maser Atomic Clocks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Food Service Equipment Market Hits $41.47B in 2025, Poised for 7% CAGR Through 2032
By PW Consulting, 2026-09-16
The Strategic Value of the 2026 Food Service Equipment Market Intelligence Report
As the global foodservice industry navigates a period of structural transformation, equipment procurement has evolved from a tactical expense to a strategic lever. The latest comprehensive study by PW Consulting on the Food Service Equipment Market offers decision-makers a rare, data-grounded compass for navigating the forecast window from 2026 through 2032. Built on a rigorous historical baseline spanning 2020 to 2025 and calibrated to forward-looking demand indicators, this research translates macroeconomic momentum, competitive realignments, and operational cost pressures into actionable intelligence tailored for executives, supply chain planners, and capital allocation teams.
For 2026 enterprise strategy, the market conversation has shifted decisively toward resilience, efficiency, and capital optimization. The industry is operating under a dual narrative: sustained revenue expansion coexisting with intensifying margin scrutiny, labor cost escalation, and raw material volatility. Our report captures this complexity without oversimplifying it, providing the structural clarity required to time investments, prioritize categories, and anticipate competitor moves. Rather than presenting a static snapshot, the analysis maps the trajectory of market growth, identifies concentration patterns, and outlines the operational and regulatory forces that will dictate procurement velocity over the next seven years.
Macro Trajectory: Mapping the Growth Arc and Capital Allocation Window
The historical record demonstrates a clear and accelerating expansion pattern. Between 2020 and 2025, the global market for foodservice equipment advanced from approximately 29.6 billion USD to 41.5 billion USD, reflecting consistent demand recovery, channel stabilization, and an expanding base of commercial kitchen operators. More importantly, the forecast period from 2026 to 2032 positions the market on a sustained upward trajectory, with projected revenue reaching 44.5 billion USD in 2026 and continuing to climb toward the mid-60 billion USD range by 2032.
This growth curve is not merely a function of volume recovery; it reflects structural demand drivers that favor deliberate, phased investment. The forecast period coincides with a phase in which labor economics, energy compliance expectations, and operational throughput requirements increasingly influence equipment specification decisions. For 2026 decision-makers, this trajectory carries two immediate implications. First, it validates a medium-to-long-term capital planning horizon rather than opportunistic purchasing. Second, it signals that the most consequential procurement decisions will be those that balance upfront cost with downstream efficiency, maintenance predictability, and regulatory alignment.
The compounding annual growth rate embedded in the forecast underscores a market that continues to expand at a meaningful pace even as operators tighten capital discipline. That combination creates a strategic tension that the report addresses directly: how to capture growth opportunities without overextending operational budgets or misreading regional and segment-level demand signals. The analysis is structured to help executives differentiate between broad market momentum and the narrower pockets of acceleration that should drive category-specific investment.
Competitive Architecture: Concentration, Positioning, and Strategic Implications
One of the most valuable elements of the report is its dissection of the competitive landscape. The market is not fragmented in a way that rewards undifferentiated pricing competitions; instead, it exhibits meaningful concentration among manufacturers that combine scale, brand breadth, and category specialization. The data indicates that the top three players collectively account for 38.5 percent of the market, while the top five represent 52.6 percent. Such concentration shapes channel dynamics, pricing agency, and the strategic weight of partnerships, service networks, and product roadmaps.
The competitive field includes organizations with distinctly different strategic postures. Some manufacturers compete on broad portfolio coverage and multi-brand architecture, spanning ranges, ovens, refrigeration, dishwashing systems, and ancillary kitchen infrastructure. Others differentiate through category leadership, leveraging deep engineering focus on specific equipment classes such as combi-steam ovens, ice production systems, beverage equipment, or heavy-duty mixing and cooking platforms. A third competitive vector is corporate ownership and consolidation activity, which influences product integration, regional distribution reach, and strategic prioritization across North America, Europe, and Asia Pacific.
Food Service Equipment Market
Recent developments highlight the pace and direction of competitive maneuvering. Mid-2025 product launches have targeted cost-conscious operators with refreshed refrigeration offerings, while facility expansions and experiential customer centers have reinforced service, demonstration, and specification support capabilities. Partnerships with institutional bodies have opened grant-assisted upgrading pathways for school meal kitchens, reflecting a broader pattern in which manufacturers increasingly align product strategy with public-sector and community nutrition programs. Leadership transitions in major multinational operations point to renewed focus on North American execution and portfolio alignment. Meanwhile, trade show demonstrations of energy-recovery systems illustrate the growing prominence of operational efficiency as a competitive differentiator rather than a compliance afterthought.
For 2026 strategy teams, this competitive architecture matters because it determines the realistic set of procurement alternatives, negotiation leverage, and vendor dependency risks. The report does not simply list competitors; it evaluates how portfolio scope, ownership structures, and recent strategic moves influence market behavior. That perspective allows buyers and investors to interpret supplier announcements with greater contextual accuracy and to anticipate which firms are likely to expand capacity, reprice offerings, or redirect innovation investment.
Operational and Regulatory Forces Reshaping Procurement Logic
Market size and competitive structure tell only part of the story. The real strategic value of the report emerges in its treatment of the forces that alter equipment selection criteria, total cost of ownership, and deployment timing. One of the most prominent is the labor cost trajectory in food services and drinking places. Rising average hourly earnings between 2025 and early 2026 have intensified the operational case for labor-saving equipment, automated food preparation, and holding solutions that reduce hands-on station time. In this environment, equipment is increasingly evaluated not only for throughput and durability but also for its contribution to workforce productivity and shift scalability.
Food Processing Equipment Market
Parallel to this, raw material dynamics continue to influence manufacturing economics. Volatility in steel and aluminum markets affects the cost structure of equipment components and, by extension, the pricing stability and lead-time predictability that operators rely on when planning capital projects. The report situates these material pressures within a broader procurement rhythm, helping organizations anticipate where cost variability may be absorbed by manufacturers, passed through to buyers, or mitigated through design engineering and supply chain adjustments.
Regulatory expectations also form a critical layer of the strategic landscape. ENERGY STAR certification and similar energy-efficiency frameworks have become practical gateways to utility incentives and compliance with evolving efficiency standards for dishwashers, ice machines, fryers, and other commercial kitchen assets. At the same time, equipment must satisfy electrical safety, gas safety, pressure vessel, and food contact material requirements to secure market access. These requirements are not static checkboxes; they shape product roadmaps, specification guidelines, and the cost-benefit calculus of choosing one equipment category over another.
The report also addresses reimbursement pathways that affect institutional demand. In the school nutrition segment, for example, equipment grants tied to USDA meal program upgrades can meaningfully offset capital costs for kitchen modernization projects. Recognizing where grant mechanisms, incentive structures, and compliance requirements intersect enables operators and contractors to design procurement plans that align with available financial support and regulatory timelines. For 2026 planning, this is especially relevant because public-sector and institutional budgets often move on different calendar cycles than commercial operators, and misreading those cycles can lead to missed windows or suboptimal specification choices.
What the Report Delivers: Operational Content for 2026 Decision-Making
This study is engineered for practical use rather than abstract commentary. It integrates historical performance, forward forecasts, competitive context, and market dynamics into a single framework that can be directly applied to budgeting, sourcing, and investment planning. The report content is organized to support several high-value decisions.
First, it provides a structured view of the market by type, application, and geography, allowing readers to identify where demand is concentrated and how segment-level priorities differ. Rather than presenting uncontextualized splits, the analysis interprets these dimensions in relation to operational realities, such as the differing equipment intensity of full-service restaurant environments versus quick-service formats, and the implications of institutional, catering, and hospitality use cases for equipment specification and replacement cycles.
Second, the report examines the competitive set with enough granularity to inform vendor selection and partnership strategy. It profiles leading manufacturers across multiple categories and geographies, noting their core product competencies, brand footprints, and recent strategic actions. This enables readers to map competitors not as isolated names but as participants in a competitive system defined by portfolio breadth, specialization, regional execution, and corporate ownership.
Third, the study incorporates the latest industry developments and regulatory signals that influence near-term planning. Product launches, facility investments, partnership activity, leadership transitions, and trade show initiatives are evaluated for their strategic relevance, while regulatory, material, and labor-market facts are integrated into the broader demand narrative. The goal is to equip decision-makers with the context needed to distinguish transient noise from durable trend shifts.
Fourth, the report addresses total cost of ownership considerations that often get overlooked in category-level discussions. Energy efficiency eligibility, labor productivity impact, maintenance expectations, and compliance readiness all have implications for long-term operating expense. By connecting these factors to market structure and procurement behavior, the analysis helps organizations evaluate equipment decisions with a fuller financial lens. For 2026 strategy, that lens is essential because capital availability, operational efficiency, and regulatory alignment increasingly converge in the same purchasing decision.
Finally, the report is designed to be referenced, not merely read. Its structure supports scenario planning, category prioritization, and procurement scheduling. Whether an organization is evaluating a kitchen modernization program, planning a multi-site rollout, assessing vendor consolidation opportunities, or modeling category growth under different labor and energy assumptions, the research provides the framing necessary to reduce uncertainty and improve decision quality.
How to Use This Intelligence for 2026 Planning
The most effective use of this report is to align market intelligence with an organization's procurement calendar, capital constraints, and operational goals. For manufacturers and distributors, the analysis supports product portfolio prioritization, geographic focus, and competitive positioning. For operators and contractors, it informs specification strategy, replacement-cycle timing, and energy-efficiency investment decisions. For investors and market entrants, it clarifies concentration dynamics, growth concentration, and the practical barriers created by regulatory and supply-chain requirements.
Because the study deliberately abstracts away segment-level percentage detail and specific regional or application amounts in this overview, the complete dataset remains essential for precise planning. The published version provides the granular breakdowns, comparative context, and working-level detail required to translate strategic direction into operational execution. Decision-makers who rely only on summary-level figures risk missing the segment-specific signals that determine where and when capital should be deployed.
Conclusion: A Deliberate Framework for a Changing Market
The Food Service Equipment Market in 2026 is not simply expanding; it is being reshaped by labor economics, energy compliance, raw material variability, and a competitive landscape in which concentration and specialization both matter. The PW Consulting market research is designed to help organizations navigate that environment with confidence by combining historical rigor, forward forecast discipline, and practical competitive analysis into a single decision-support resource.
The report offers the breadth and depth needed to inform capital allocation, procurement strategy, and competitive positioning without overloading readers with uncontextualized data. Its true value lies in helping organizations distinguish durable growth from temporary momentum and to align equipment strategy with the operational realities that will define the next several years. For those preparing for 2026 and beyond, the complete report provides the detailed segment and regional intelligence required to move from strategic direction to informed execution.
For detailed analysis of this topic, please visit the official page: Food Service Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: POCT Market Hits $215M in 2025, Projects $377.98M by 2032 at 8.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Point-of-Care Testing Landscape: Strategic Insights for 2026 and Beyond
The global healthcare delivery model is undergoing a fundamental structural shift, moving diagnostics from centralized laboratories to the patient's side. As we enter 2026, Point-of-Care Testing (POCT) is no longer merely a convenience but a critical infrastructure component for resilient health systems. PW Consulting's latest comprehensive market research provides a definitive roadmap for stakeholders navigating this high-growth environment. This analysis synthesizes historical performance with forward-looking projections to underscore the strategic imperative of understanding this market's trajectory.
The market has demonstrated remarkable resilience and growth over the past half-decade. Valued at approximately 163 million USD in 2020, the industry navigated volatility before establishing a robust upward trend. By 2025, the market size stabilized around 215 million USD, setting the stage for accelerated expansion. Our forecast period, spanning from 2026 to 2032, indicates a compound annual growth rate of 8.5 percent. This growth suggests the market could approach close to 378 million USD by the end of the decade, driven by aging demographics, the prevalence of chronic diseases, and the enduring demand for rapid diagnostic results.
Lateral Flow POC Reader Market
Strategic Value for Enterprise Decision-Making
For executives and investors, understanding the aggregate numbers is only the first step. The true value of this research lies in dissecting the underlying drivers that will dictate capital allocation and product development strategies in 2026. The transition to decentralized testing is creating new value chains, altering reimbursement landscapes, and reshaping competitive dynamics. Our report moves beyond surface-level statistics to offer actionable intelligence on where value is being created and how market share is being contested.
Decision-makers need to anticipate regulatory shifts that could alter compliance costs and market access. Similarly, understanding the concentration of power among top-tier vendors is essential for assessing supplier risk and partnership opportunities. The following sections detail the operational depth included in the full study, designed to mitigate risk and identify high-probability growth avenues.
Operational Scope and Analytical Depth
This market research is constructed to serve as a practical toolkit for strategy formulation. It bridges the gap between high-level market sizing and on-the-ground commercial execution. Readers will find granular analysis covering the entire ecosystem, from manufacturing inputs to end-user adoption patterns.
-
Technology Segmentation Analysis: The report categorizes the market by testing type, including glucose monitoring, infectious disease testing, cardiometabolic testing, and other emerging categories. We analyze the adoption curves and technological maturity of each segment to predict future revenue mix shifts.
-
End-User Application Drivers: Special attention is given to the settings where testing occurs, such as hospital bedside, physician offices, and home self-testing environments. Understanding the unique procurement cycles and regulatory requirements of each application is vital for market entry strategies.
-
Regional Market Dynamics: We examine performance across key geographic territories, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. This analysis highlights varying levels of market maturity and infrastructure readiness without limiting the scope to static regional snapshots.
-
Supply Chain and Manufacturing Insights: The study evaluates the operational capabilities required to scale POCT devices and consumables, considering reagent stability, device portability, and connectivity requirements.
Competitive Landscape and Key Player Strategies
The POCT market is characterized by a mix of established diagnostics giants and specialized innovators. Our analysis provides detailed profiles of the core companies shaping the industry, evaluating their product portfolios, strategic positioning, and recent market activities. The competitive intensity is notable, with a significant portion of revenue concentrated among the top firms, indicating high barriers to entry and strong brand loyalty.
Major Incumbents and Product Portfolios
Leaders in the space are leveraging diverse technological platforms to capture share across multiple testing categories. Abbott Laboratories, headquartered in Abbott Park, Illinois, continues to strengthen its position with the i-STAT system and the ID NOW rapid molecular platform, alongside the Alinity i for various markers. These offerings span cardiac, infectious, and metabolic testing, providing a broad suite for clinical settings.
F. Hoffmann-La Roche Ltd, based in Basel, Switzerland, is focusing on molecular precision with the cobas liat system. Their recent activities highlight a push toward multiplex testing capabilities at the point of care, enabling rapid detection of multiple targets simultaneously. Siemens Healthineers AG from Erlangen, Germany, offers comprehensive solutions for blood gas, cardiac, and routine testing, utilizing high-throughput analyzers that bridge the gap between central lab efficiency and point-of-care speed.
Danaher Corporation, located in Washington, D.C., leverages its subsidiary strengths through Cepheid GeneXpert and Beckman Coulter platforms. These tools address molecular and immunoassay needs, catering to complex diagnostic requirements in varied care settings. QuidelOrtho Corporation in San Diego, California, maintains a strong presence with Sofia fluorescent analyzers and QuickVue lateral flow tests, focusing on rapid immunoassay POCT for infectious diseases. Becton, Dickinson and Company (BD), based in Franklin Lakes, New Jersey, provides the Veritor system and other rapid diagnostic platforms, covering both molecular and immunoassay tests to support decentralized testing initiatives.
bioMérieux SA, headquartered in Marcy-l'Étoile, France, contributes with the BIOFIRE and VITEK 2 systems, emphasizing rapid molecular and automated solutions for critical care environments. Thermo Fisher Scientific Inc., from Waltham, Massachusetts, rounds out the key player list with rapid diagnostic and molecular test solutions tailored for infectious diseases and clinical POCT applications.
Point-of-Care Testing (POCT) Market
Recent Strategic Moves and Regulatory Milestones
Market velocity is often dictated by regulatory approvals and strategic consolidations. Our report tracks these events to provide context on market readiness. In early 2025, Roche received FDA clearance with a CLIA waiver for cobas liat STI multiplex panels, expanding the utility of their platform for point-of-care use in sensitive testing scenarios. Later that year, in July 2025, BD received FDA 510(k) clearance for the BD Veritor System for SARS-CoV-2 rapid point-of-care testing, transitioning from emergency use authorization to standard clearance, which signals a maturation in the regulatory pathway for respiratory diagnostics.
Strategic consolidation is also reshaping the landscape. In June 2025, QuidelOrtho announced its intent to acquire LEX Diagnostics, contingent on U.S. FDA clearance for the VELO respiratory POCT system. This move included plans to discontinue the Savanna platform, indicating a strategic pivot toward next-generation respiratory testing technologies. Additionally, independent developments such as SEKISUI Diagnostics launching new rapid diagnostic tools for RSV detection in professional healthcare settings during May 2025 highlight the ongoing innovation pipeline beyond the major conglomerates.
Regulatory Dynamics and Industry Standards
The operational environment for POCT is heavily influenced by regulatory frameworks that ensure test accuracy and reliability. A significant update occurred in January 2025, when full effects of CLIA regulatory updates for point-of-care testing went into place. These updates included enhanced proficiency testing requirements with a performance range of plus or minus 8 percent for analytes like hemoglobin A1C. Such regulations directly impact device validation, quality control protocols, and the cost structure for providers implementing POCT solutions.
Understanding these regulatory nuances is critical for any organization planning to introduce new tests or expand existing ones. Our research details how these compliance requirements affect different testing types and regions, offering guidance on navigating the approval processes and maintaining operational compliance without stifling innovation. The interplay between regulatory bodies and market innovation defines the pace at which new technologies can be deployed to patients.
Market Concentration and Future Outlook
The competitive structure of the POCT market suggests a consolidated environment where scale and technological breadth are key advantages. Our data indicates a concentration ratio among the top three and top five firms that underscores the dominance of established players. This concentration influences pricing power, supply chain negotiations, and the ability to invest in R&D for next-generation platforms.
Looking toward 2032, the trajectory points toward increased integration of digital health solutions with physical testing devices. Connectivity, data interoperability, and automated result reporting will likely become standard expectations rather than differentiators. The growth from 228 million USD in 2026 to nearly 378 million USD by 2032 represents not just revenue expansion but a transformation in how healthcare data is generated and utilized.
Investors and corporate strategists must consider how these long-term trends align with their portfolios. The shift toward home self-testing and physician office-based testing continues to rise, challenging traditional hospital-centric models. Each segment presents unique challenges regarding reimbursement, user education, and device usability. Our full report provides the segmented data necessary to model these scenarios accurately.
Unlock the Full Intelligence
This overview serves as a strategic preview of the comprehensive intelligence available in PW Consulting's full Point-of-Care Testing Market Report. While the macro trends and competitive dynamics outlined here provide a strong foundation, the detailed segmentation data, specific regional revenue estimates, and granular application breakdowns are essential for precise planning. The specific numerical splits across regions, testing types, and applications reveal the nuanced opportunities that aggregate data obscures.
Access to the complete dataset allows stakeholders to benchmark their internal targets against market realities, identify underserved niches, and anticipate competitor moves with greater accuracy. The detailed profiles of key companies, including specific product positioning and recent development timelines, offer a clear view of the battlefield. For procurement teams, the insights into supplier concentration and regulatory requirements inform risk management strategies.
To leverage these insights for your 2026 planning cycle, we invite you to access the full report web page. There you will find the complete quantitative models, deep-dive case studies, and actionable recommendations tailored to drive growth in the evolving POCT landscape. Do not rely on partial data for critical strategic decisions; obtain the complete intelligence package to secure a competitive advantage in this high-growth market.
The window for strategic positioning in the Point-of-Care Testing market is open, but the landscape is shifting rapidly. Armed with the right intelligence, organizations can navigate regulatory changes, capitalize on technological advancements, and capture value in a market poised for significant expansion. PW Consulting remains committed to providing the clarity needed to turn market complexity into strategic opportunity.
For detailed analysis of this topic, please visit the official page: Point-of-Care Testing (POCT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
P.W. Consulting Reveals Feminine Care Sanitary Napkin Market to Reach $344.8M by 2032, 6.98% CAGR
By PW Consulting, 2026-09-16
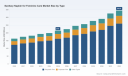
Strategic Intelligence for the Sanitary Napkin for Feminine Care Market Through 2032
The global feminine hygiene sector stands at a critical inflection point. As consumer expectations evolve and regulatory frameworks mature, decision-makers require more than headline figures. They need a structured, evidence-based view of how the sanitary napkin for feminine care market will compound, where competitive pressure will concentrate, and which operational capabilities will separate resilient players from the rest. The newly released PW Consulting market study translates a decade of historical performance and a seven-year forward trajectory into a decision-ready toolkit for 2026 strategy planning.
This overview outlines the analytical architecture of the report, demonstrates how the macro trajectory anchors strategic planning, and previews the competitive and regulatory dimensions that will shape portfolio choices, manufacturing footprints, and go-to-market investments. Detailed segment valuations, regional breakdowns, and company-level scenario models are reserved for the full dataset, ensuring that executives who engage with the complete study gain exclusive access to the full intelligence stack.
Market Trajectory and the Strategic Baseline for 2026
The sanitary napkin for feminine care market has navigated a clear growth corridor over the past half-decade. Historical tracking from 2020 through 2025 shows a steady climb in absolute revenue, reflecting sustained demand, incremental product innovation, and broader distribution penetration across mature and emerging channels. This historical arc establishes the baseline against which forward-looking assumptions are stress-tested in the forecast window extending to 2032.
The forward trajectory projects continued expansion at a compound annual growth rate of 6.98 percent across the forecast period. Such a rate signals more than incremental volume accumulation; it points to structural tailwinds that reward companies able to align product architecture, supply chain agility, and compliance readiness with shifting consumer preferences. For 2026 planning teams, the key implication is that growth will not accrue uniformly. Revenue will concentrate around specific value propositions, manufacturing capabilities, and regional execution quality, making segmentation intelligence indispensable for capital allocation.
PW Consulting’s analysis converts this trajectory into a planning framework. Instead of treating the forecast as a single line item, the study maps how different product architectures, application contexts, and operational models contribute to the cumulative outcome. This approach allows leadership teams to test sensitivity around pricing, mix shifts, capacity utilization, and regulatory compliance costs without relying on blunt averages. The result is a clearer picture of where margin potential exists and where execution risk is most likely to erode returns.
Because the market’s expansion is coupled with tightening oversight and intensifying brand competition, the strategic question for 2026 is no longer whether the sector will grow, but how to position within that growth. The report is built to answer that question through disciplined segmentation, competitive benchmarking, and scenario planning that can be operationalized across commercial, procurement, and regulatory functions.
What the Report Delivers: Architecture of Actionable Intelligence
A market study earns its place in the executive workflow only when it converts data into decisions. The PW Consulting report is organized around practical deliverables that support strategy formulation, investment prioritization, and risk management. The content is designed to be referenced directly in planning cycles rather than read once and shelved.
Core Analytical Components
- Historical market reconstruction that ties observed performance from 2020 to 2025 to the assumptions driving the forecast through 2032
- Segment-level assessment of product-type dynamics and application contexts, enabling a precise reading of where demand intensity and competitive overlap are highest
- Market concentration analysis that quantifies how revenue is distributed across leading players and what that implies for entry barriers, pricing power, and partnership strategy
- Competitive profiling of key enterprises, including headquarters positioning, brand portfolios, and recent strategic moves that signal future capability builds
- Regulatory and standards monitoring that tracks classification, testing expectations, labeling guidance, quality management alignment, and emerging global standardization activity
- Scenario-ready framing that lets teams evaluate how shifts in compliance cost, raw material strategy, channel mix, and brand positioning could alter outcomes within the forecast horizon
Each component is interlinked. Historical performance informs segment assumptions; segment dynamics clarify competitive positioning; competitive positioning shapes partnership and private-label decisions; and regulatory trajectory defines the compliance ceiling that every manufacturer must accommodate. By presenting these layers together, the report gives executives a coherent map rather than isolated data points.
Importantly, the study preserves analytical rigor without overwhelming the reader with raw tables. Narrative interpretation accompanies the numbers so that teams can understand not only what the figures are, but why they matter and how they should influence resource allocation. For confidentiality and commercial focus, granular regional shares and application-level monetary splits are disclosed in the full report, ensuring that subscribers receive the depth required for precise planning while this overview maintains the strategic preview format.
Competitive Landscape: Convergence, Differentiation, and Strategic Moves
The sanitary napkin for feminine care market is shaped by a mix of global multinationals, regional specialists, and manufacturing partners serving private-label and OEM/ODM channels. The competitive field reflects differing strategic priorities: some companies compete through brand heritage and broad distribution, others through product technology and softness claims, and still others through cost-efficient manufacturing and regulatory readiness for specific markets.
Key Enterprise Positioning
- Kimberly-Clark Corporation, based in Irving, Texas, maintains a prominent brand presence through Kotex sanitary napkins and panty liners, with distribution and partnership activity that extends into essential-care initiatives
- Unicharm Corporation, headquartered in Ehime, Japan, competes through the Sofy line of sanitary napkins and panty liners, reinforcing its position in markets where comfort, fit, and consumer trust are decisive purchase drivers
- Kao Corporation, located in Tokyo, Japan, advances the Laurier brand and has emphasized product refinements aimed at improving softness and breathability, aligning innovation with everyday usage expectations
- Hengan International Group Company Limited, operating from Jiangxi, China, manages brands such as Space7 and Anerle, reflecting a portfolio approach that targets value-conscious and mid-tier consumer segments
- Family Cares Group, based in Fujian, China, produces Ecolivia sanitary napkins and maintains quality-system and registration credentials that support traceability and compliance-oriented positioning
- Premier Care Industries, headquartered in Winnipeg, Manitoba, Canada, manufactures sanitary napkins and liners under the Bodyform brand for private-label and national-equivalent channels, highlighting the strategic role of contract and brand-transfer models
- Ontex Group NV, based in Aalst, Belgium, participates across feminine hygiene sanitary napkins and liners, with a footprint that supports multi-market execution and product range breadth
- Haoyue Personal Care Co., Ltd., from Hangzhou, Zhejiang, China, operates in the OEM/ODM space, serving as a manufacturing partner for brands that require flexible production and specification customization
The competitive story is not simply a ranking of scale. It is a study in how companies allocate effort across brand building, product engineering, channel access, and manufacturing efficiency. In this market, a player with strong brand recognition may still face pressure if regulatory expectations rise or if a competitor secures a meaningful advantage in comfort, absorbency, or cost structure. Likewise, manufacturers serving private-label and OEM/ODM customers have a different risk profile: they must align with client specifications, quality expectations, and compliance documentation while maintaining production reliability.
Recent Strategic Signals
Recent activity among leading participants illustrates how the competitive field is being shaped in real time.
- In October 2025, Kimberly-Clark Corporation expanded global partnerships with Baby2Baby, Plan International, Project HOPE, and UNICEF to advance essential care for women and girls, signaling a broader corporate commitment that intersects with brand visibility and social-impact positioning
- In April 2024, Unicharm Corporation entered a strategic partnership with Kao Corporation, a move that underscores how collaboration can reshape distribution leverage, product development velocity, and market access
- In 2024, Kao Corporation introduced advanced Ultra-Soft Technology in Laurier products, enhancing softness and breathability, an example of product-level differentiation intended to reinforce consumer preference in a crowded category
These developments matter because they show where competitors are investing attention. Partnerships can accelerate reach and credibility. Product innovations can shift purchase criteria. Regulatory and quality milestones can define who is eligible to compete in more demanding channels. The report uses these signals to build a living picture of competitive momentum rather than a static list of players.
Tampons Market
Regulatory Evolution and Quality Infrastructure as Strategic Variables
Regulatory dynamics are no longer peripheral to commercial strategy in feminine care. They influence product design, testing protocols, labeling clarity, quality management systems, and market access. For 2026 and beyond, compliance readiness is a competitive variable, not just a legal checkbox.
Classification and Testing Expectations
Sanitary napkins are classified by the FDA as Class II medical devices, and in October 2025 the agency issued draft guidance for performance testing and labeling. The guidance includes recommendations for pads to ensure safe absorption and to provide clear directions for use. This development points to an environment where substantiation, transparency, and consistent product performance are increasingly central to market acceptance.
Sanitary Napkin for Feminine Care Market
Quality Management Alignment
Effective February 2, 2026, the FDA QMSR incorporates ISO 13485:2016 into 21 CFR Part 820, extending its relevance to menstrual products including sanitary napkins. For manufacturers, this alignment raises the importance of documented quality processes, traceable controls, and system-level consistency. Companies that already operate mature quality frameworks will face a different adaptation burden than those building compliance capability from the ground up.
Certification and Standards Momentum
Standards activity is also advancing. ISO/TC 338 is developing global standards for single-use menstrual pads, including sanitary napkins, with expected completion in December 2026. In parallel, certain manufacturers maintain ISO 9001:2015 certification and FDA establishment registration credentials that support export readiness and buyer confidence. These elements collectively indicate that the market is moving toward more formalized expectations around product consistency and documentation.
Strategically, the implication is clear. Product claims, absorption performance, and user instructions will be judged against a more defined oversight environment. Supply chains, manufacturing sites, and product-development timelines must account for the time and cost of validating performance and maintaining compliant quality systems. The report integrates these regulatory currents into the forward assessment so that strategy teams can anticipate operational impact rather than react after the fact.
How to Use This Study for 2026 Decision-Making
The value of a market study lies in its deployment. For 2026 planning, the PW Consulting research is structured to support several concrete uses.
Portfolio and Product Strategy
Leadership teams can use the segmentation architecture to determine where to reinforce existing offerings, where to introduce product refinements, and where to avoid overinvestment in crowded or low-differentiation positions. The forward trajectory and segment interpretation help frame whether resources should tilt toward comfort and breathability, absorption reliability, sustainability positioning, or channel-specific packaging and sizing.
Competitive and Partnership Planning
The competitive profiles and recent moves provide a basis for assessing partnership opportunities, private-label potential, and brand-transfer dynamics. Companies evaluating collaboration can better understand which partners bring distribution strength, which bring product technology, and which bring manufacturing flexibility. This is particularly relevant in a market where OEM/ODM capabilities and national-equivalent branding both play meaningful roles.
Compliance and Operational Readiness
With evolving guidance, QMSR alignment, and international standards development, the study gives teams a structured basis for compliance planning. Product, quality, and regulatory functions can use the framework to anticipate documentation needs, testing expectations, and system updates, thereby reducing the risk of late-stage remediation.
Scenario and Investment Planning
Because the forecast spans to 2032, executives can test investment horizons against multiple assumptions. Capacity expansion, geographic focus, brand investment, and compliance spending can all be evaluated in the context of a compounding market trajectory rather than a single-year snapshot. That longer lens helps distinguish short-lived opportunities from durable structural growth.
Why the Full Dataset Matters
This overview has intentionally presented the strategic scaffold while reserving the detailed segment magnitudes, regional distributions, and application-level monetary splits for the complete report. That design reflects how executive intelligence should work: enough transparency to establish credibility and demonstrate analytical depth, while preserving the full economic granularity that drives precise planning.
Subscribers to the full study gain access to the complete segmentation values, market concentration detail, competitive profiling, and scenario framing needed to convert the 6.98 percent compound trajectory and the broader 2020-to-2032 arc into actionable investment decisions. For teams responsible for 2026 budgeting, channel strategy, product roadmaps, or regulatory readiness, the full dataset provides the resolution required to move from directional confidence to specific commitment.
Closing Perspective
The sanitary napkin for feminine care market is expanding within a context defined by consumer-refinement pressure, intensifying brand and manufacturing competition, and a maturing regulatory environment. Growth is real, but its value will be captured by organizations that can align product differentiation, compliance discipline, and competitive positioning with a clear view of where demand and margin will concentrate.
PW Consulting’s study is designed to make that alignment practical. It connects historical evidence, forward projections, competitive behavior, and regulatory direction into a single planning framework. For executives preparing 2026 decisions, the report offers both the strategic narrative and the operational detail needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Sanitary Napkin for Feminine Care Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com